November 6, 2026
Bonus Content: Target’s P/E Is Half of Walmart’s. Holiday Quarter Is the Test.
Below is an important message from one of our highly valued sponsors. Please read it carefully as they have some special information to share with you.
Dear reader,
This might be the most valuable document I’ve ever uncovered.

What’s under the black bars could change your life forever.
Elon quietly filed this document with the federal government.
And what’s inside could be bigger than Tesla, SpaceX, and xAI combined.
Big enough, I believe, to mint a record breaking wave of new “Musk Millionaires” over the coming years…
That’s because Elon is going after the largest cash pile in history.
Artificial Intelligence.
And what is in this filing proves he is about to make Bezos, Altman and Zuckerberg beg for mercy.
Look…
I called NVIDIA in 2008, Bitcoin in 2013, and his Super IPO years before they turned everyday Americans into millionaires.
And what Elon is doing next could be the biggest money making opportunity of them all.
Luckily, almost nobody knows this exists.
But it won’t stay quiet for long. Once it goes mainstream, your chance to get in early is gone.
If you missed out on Tesla…
If you missed out on Bitcoin…
If you missed out on NVIDIA…
>>> DON’T MISS THIS ONE TOO <<<
>>> CLICK HERE TO SEE HOW YOU CAN GET IN ON ELON’S NEXT MILLIONAIRE MAKER <<<
This could be your final shot to make up for every other opportunity you’ve missed.
Don’t let one more click and two more minutes of your time be the reason you miss out again.
Regards,
James Altucher
Target’s P/E Is Half of Walmart’s. Holiday Quarter Is the Test.
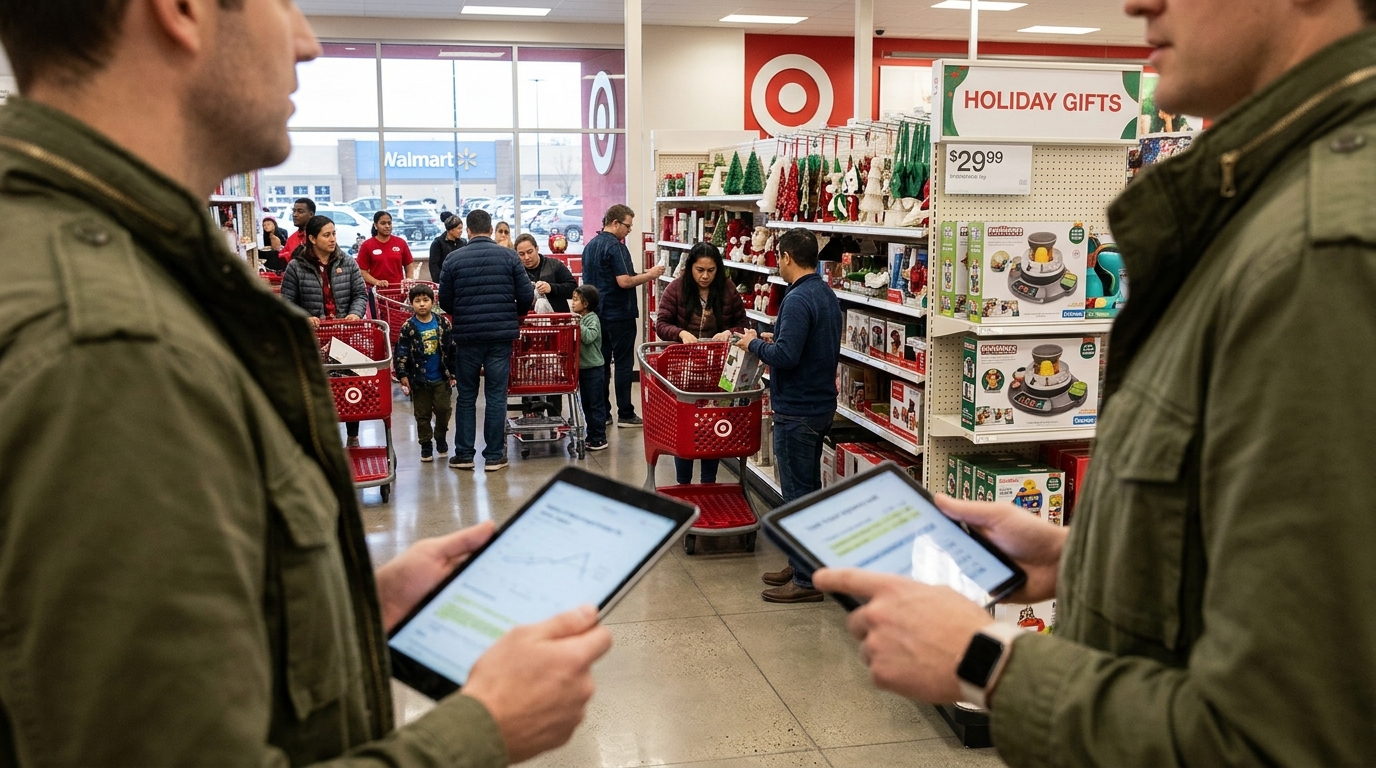
Twelve days from now, Target reports its fiscal third-quarter results. The number that matters most will not be EPS. It will be comparable sales, because that is the data point that tells investors whether CEO Michael Fiddelke’s turnaround plan has real legs heading into the heaviest spending weeks of the year.
Target currently trades at a trailing P/E of roughly 16x. Against its direct peers the gap is wider. Even after a substantial run from its lows, Target sells at approximately the high-teens multiple of earnings, far below Walmart and Costco, which trade at materially higher multiples. Paying 16 to 18 times for a business with more than 2,000 stores, a retail media network, and a strengthening dividend record is not a crowded position.
The valuation gap between Target and Walmart is not just a number — it reflects what the market demands from each business. Walmart’s guidance miss showed how little room a 49x multiple leaves for anything short of perfect execution every quarter.
TGT has grown its dividend for 54 consecutive years, with an average annual increase of 11.02% over the past five years. The latest quarterly dividend of $1.16 represents a 1.8% increase from the previous $1.14 distribution. Walmart and Costco yield less, making Target the only big-box retailer generating meaningful income for dividend-focused investors at current prices.
The business itself is recovering faster than the multiple reflects. Same-store sales rose 5.6% in Q1, the first positive reading in five quarters. After the company’s Q2 results, UBS raised its price target to $185 and kept a Buy rating, pointing to a 3.8% increase in comparable sales. HSBC also upgraded the stock to Buy from Hold and set a $190 price target, citing the potential for earnings recovery.
Analysts expect Target to report Q3 earnings of $2.08 per share on a diluted basis, up 16.9% from $1.78 per share in the year-ago quarter. The company has consistently surpassed Wall Street’s EPS estimates in its last four quarterly reports, which removes some of the binary risk around the November 18 results. The National Retail Federation’s 2026 holiday forecast calls for November and December retail sales to rise 4.2% versus 2025, totaling about $1.013 trillion, which would put a solid demand backdrop behind the critical November and December weeks that follow.
The risks are real. Intensifying competition and traffic pressure remain concerns that could restrain the earnings multiple. After-tax return on invested capital for the trailing twelve months through Q1 2026 was 12.4%, down from 15.1% in the same period a year earlier, a gap the management team needs to close for the valuation argument to fully hold.
The wealth-building case here is not momentum. It is reversion. When a business with a half-century dividend growth streak, a market cap measured in the tens of billions, and recovering same-store sales trades at less than half the multiple of its nearest comparable peer, the question is not whether the discount is deserved. The question is how long it lasts.