October 31, 2026
Bonus Content: ACA Premiums Rise Again: What It Means for Your Budget
Former tech executive Jeff Brown, the man who picked Nvidia in 2016, before it jumped as high as 37,800%, just got inside a Cybercab, Elon Musk’s new car that has no steering wheel or pedals… and what happens will shock everyone. Click here to see the details or read more below.
Dear Reader,
This man you see below just got inside a Cybercab…
Elon Musk’s new car that has no steering wheel…
No gas or break pedals…
And no rearview mirrors.
You won’t believe what happened next.
Click here to see this exclusive Cybercab footage
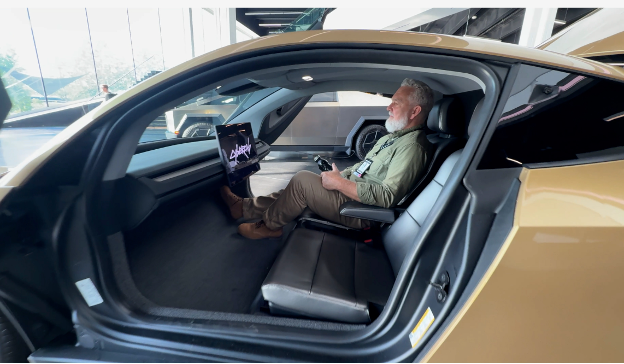
And get the details on why Elon is predicting his next move could help unleash $320 trillion in new wealth…
And how you could claim your piece of that pie.
Regards,
Lindsey Hough
Managing Director, Brownstone Research
ACA Premiums Rise Again: What It Means for Your Budget
The ACA Marketplace 2027 open enrollment period starts November 1. For the roughly 20 million Americans still buying coverage on their own, this season is unlike any in recent memory. The enhanced premium tax credits that first arrived during the pandemic under the American Rescue Plan and were extended through 2025 by the Inflation Reduction Act expired on December 31, 2025, reverting subsidy rules to the ACA’s original, less generous structure. Congress has not brought them back. The enrollment window that opens Sunday is the first full season priced entirely without them.
ACA marketplace premiums face a median 15% increase for 2027, the second consecutive double-digit hike. It is among the highest requested premium increases for the marketplace since 2018, with filings pointing to rising health care costs and a sicker remaining risk pool as key drivers.
What the Numbers Mean for a Household Budget
When the enhanced credits expired for 2026, the average premium payment rose 58%, and deductibles jumped 37% as people shifted to bronze plans. The average marketplace deductible climbed by more than $1,000, to $3,786. Now another 15% lands on top of that base.
Households above 400% of the federal poverty level no longer qualify for any subsidy at all, which means a family of four earning around $125,000 faces the full premium, unassisted. For the first time, if you underestimate your income, you repay every dollar of excess subsidy at tax time. That repayment cap is simply gone.
The practical response: shop actively rather than auto-renewing. Your own premium depends on your plan, age, and rating area, so check your renewal notice rather than relying on the national average. Open enrollment runs November 1 through January 15; enroll by December 15 to secure January 1 coverage. Income-eligible households should still verify subsidy eligibility under the original ACA formula, which covers incomes between 100% and 400% of the poverty level.
The Insurer Arithmetic Is More Complicated
The enrollment collapse already underway shapes every insurer decision heading into this season. Enrollment in the individual health insurance market fell by 18%, over 4.6 million people, from 25.2 million in June 2025 to 20.5 million in June 2026. The remaining risk pool likely became older and sicker. That combination, lower volume plus higher acuity, is precisely the environment that separates disciplined underwriters from those who priced for a market that no longer exists.
Molina (MOH) is the clearest cautionary signal. Molina is cutting more than half of its marketplace states, paring down to roughly six. In the second quarter, Molina’s ACA business posted a medical loss ratio of 88.9%, up 3.5 percentage points year over year. Management’s stated philosophy, as quoted by CEO Zubretsky: “Until we’re convinced that the risk pool is stable in that market, we’re going to allocate less capital to it.” Cigna is departing the exchanges for 2027, impacting roughly 369,000 to 370,000 enrollees nationally.
The disciplined-exit playbook is not unique to the ACA market. UnitedHealth is applying the same capital-allocation logic to Medicare Advantage, deliberately shedding unprofitable counties rather than defending market share.
Centene (CNC) and Oscar Health (OSCR) are reading the same map differently. Centene has said its Marketplace business remains on track. Oscar is in the middle of a major multi-year expansion in the exchanges, planning to add between 400 and 600 new counties by 2029. For 2027, Oscar is expanding into South Carolina and has said it will increase its county count by about 24% from last year.
Most people who lose exchange coverage appear to have gone uninsured. HCA Healthcare cut its profit outlook for 2026 largely due to a payer mix shift tied to patients who lost coverage on the health insurance exchanges. That uncompensated care pressure on hospital networks is the downstream consequence that equity investors in HCA (HCA) and Elevance (ELV) need to track alongside the direct insurer exposure.
The insurer retreat is not limited to the ACA exchanges. Eleven carriers are simultaneously exiting Medicare Advantage for 2027, leaving hundreds of thousands of seniors scrambling for new coverage.
The Wealth Builder Takeaway
The open question for 2027 is whether a smaller, higher-acuity risk pool can stabilize at these rates, or whether another year of double-digit increases drives further enrollment losses and more exits. Insurers that priced conservatively and trimmed exposure early, Centene chief among them, enter this enrollment season with the better hand. Those still carrying oversized ACA books at elevated loss ratios face another difficult year of pricing changes or retreat. Weekly enrollment snapshots later this month will give the first real read on whether the market is stabilizing or whether the attrition continues. Either way, the data land before most investors have updated their models.