October 31, 2026
Bonus Content: McDonald’s Reports Tuesday. Its Dividend Makes the Case Either Way.
Today, you can claim the Ultimate Dividend Package…
For FREE. (No credit card required!)
Inside, Marc Lichtenfeld – bestselling author of Get Rich with Dividends and world-renowned income expert – is giving away his top dividend picks for 2026.
You’ll get details on…
- Marc’s No. 1 dividend stock for 2026
- The safest 9% dividend in the world
- The top three “Extreme Dividend” stocks
- And much, much more!
Click here to get your FREE Ultimate Dividend Package!
Sincerely,
Rachel Gearhart
Associate Publisher, The Oxford Club
McDonald’s Reports Tuesday. Its Dividend Makes the Case Either Way.
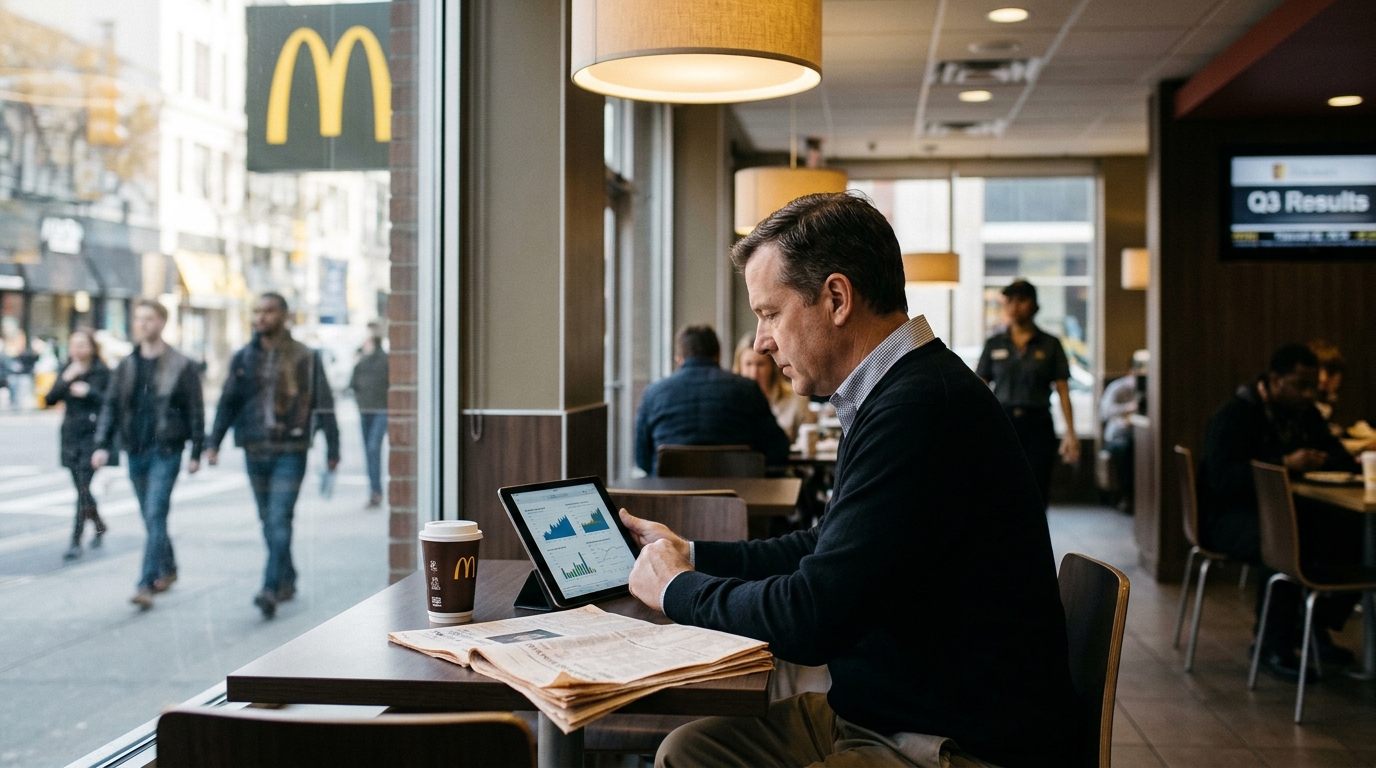
Tuesday morning, before most investors have opened their brokerage apps, McDonald’s (MCD) will drop its Q3 results. The earnings date is currently expected to be before market open on November 4. The consensus calls for earnings of about $3.3 to $3.4 per share on revenue a little above $7 billion. The number itself is almost beside the point. What matters more, heading into a holiday season defined by an anxious consumer, is what McDonald’s represents in a portfolio built for durability.
The Bigger Trend
The backdrop for this report is unusually tense. U.S. consumer confidence fell sharply in September, and The Conference Board said consumers expected both business conditions and the labor market to weaken over the next six months.
Against that, the National Retail Federation is projecting a holiday season that looks cheerful on paper. The NRF forecasts U.S. retail sales during November and December will increase 4.2% in 2026 to $1.013 trillion, accelerating from last year’s 3.1% growth to $972 billion. The tension between those two numbers is real. The NRF has said consumers are likely to prioritize the holiday season even as they stay mindful of their budgets. That is not the same as spending comfortably. It means trade-downs, coupon clipping, and value comparisons.
Your Download Link Will Expire
If you still haven’t downloaded my free “Simple Options Trading For Beginners” guide…
…please take a few seconds and download it right now before your new temporary download link expires.
I eventually plan to charge money for this training, so do yourself a favor and download it now…
That way, no matter what it costs in the future, you’ll have a free copy on your computer.
Make sense?
This is precisely the environment where quick-service value positioning matters. Chipotle just reported a margin miss even as traffic turned positive: Chipotle posted adjusted EPS of $0.27 versus $0.29 a year earlier, while revenue reached $3.3 billion, up 9.6% year over year. Operating margin declined to 13.7% from 15.9% in the prior-year period. Starbucks reported this week as well, with net revenue falling 4% to $9.14 billion and global same-store sales up 7.2%, while international comparable sales rose 0.9% as traffic declines offset a higher average ticket. The sector is navigating a bifurcated consumer, and McDonald’s enters that read in a weaker stock position than a year ago.
The sector’s bifurcation runs deeper than one quarter’s numbers suggest. Starbucks is closing 250 underperforming locations as Niccol’s restructuring tests whether the brand can recover traffic without sacrificing margin.
The Investment Case
Tuesday’s report will generate its share of price action, but the more relevant lens for long-term investors is income. McDonald’s is a Dividend King, with 50 consecutive years of dividend increases. The trailing 12-month dividend payout as of late October stands at $7.44 per share, and the stock’s yield has been hovering around the high-2% range. With the stock down meaningfully from its 52-week high, that yield is now at levels that attract income-focused buyers who would have passed a year ago.
The income case does not rest on McDonald’s alone. Other dividend fortresses with durable cash flows and credible balance sheets hold up through the same cycles income investors worry about now.
The franchise model amplifies the defensive case. McDonald’s collects royalties and rent from franchisees rather than absorbing the full weight of labor and food-cost inflation. Digital momentum, loyalty engagement, and commentary on value offerings versus premium menu innovation will signal how McDonald’s is navigating a bifurcated consumer spending environment. Those are the data points worth tracking Tuesday morning, not whether the company beat by a few cents.
Building Wealth Around This Idea
For investors thinking about the defensive corner of a portfolio, McDonald’s occupies a specific role: consistent income, low cyclical sensitivity relative to most consumer names, and a brand that benefits when budgets tighten. The Q3 report is a check-in, not a thesis-maker. In the same quarter a year earlier, McDonald’s reported $3.22 per share on revenue of $7.08 billion, and the stock has already priced in modest expectations. The more consequential question is whether McDonald’s sustains dividend growth through a holiday quarter where consumer confidence has been running near a 12-year low.
The consumer confidence backdrop shapes more than one earnings report this season. Deep promotional discounting and stretched household budgets are already determining which retailers can protect margins through the holiday quarter.
Risks to Monitor
Short-term volatility around Tuesday’s open is real. A revenue miss alongside soft U.S. same-store sales commentary would pressure the stock. The Federal Reserve’s June projections put 2026 inflation around 3.5% (fourth quarter to fourth quarter), with moderation expected after that, which means food and wage costs can stay elevated longer than franchisees would prefer. A prolonged squeeze on franchisee profitability eventually flows back to the parent through slower unit growth and reduced royalty leverage.
Daily Wealth Takeaway
When consumer confidence slides toward a 12-year low, the defensive part of your portfolio is not a hedge. It is the foundation. McDonald’s dividend history does not guarantee future income, but 50 consecutive years of raises through recessions, pandemics, and energy shocks is evidence worth weighing before Tuesday morning arrives.