November 4, 2026
Three record backlogs, a looming budget fight, and stocks trading like the contracts don’t exist. Here’s the disconnect.
Markets rarely give investors a clean second look. The aerospace and defense sector just did. The S&P 1500 Aerospace and Defense Index fell nearly 19% from an early-August high through mid-October, pricing in a Democratic sweep before a single vote was counted. That sweep is now confirmed. So the question for long-term investors is not whether the news is bad. It is whether the market already over-discounted it.
Your Balance Is a Promise, Not a Pile of Cash
Every dollar in your bank is an entry in a ledger and a claim on an institution. That works fine right up until it does not. Priority Gold’s free Wealth Preservation Guide looks at what history says about moments when those claims came under pressure, and shows three simple steps for holding part of your retirement directly.
The budget mechanics matter here. The federal government is funded through December 11, 2026, under a short-term continuing resolution signed by President Trump on September 2, avoiding an October 1 shutdown. Full-year fiscal year 2027 appropriations remain unresolved, and Congress must pass 12 regular appropriations bills or another extension before that date. The incoming Congress is not even seated yet, which means the first real budget confrontation of the new political order arrives in five weeks under the old one.
Congress appears unlikely to approve the Pentagon’s full $1.5 trillion request, which the White House divided into two parts: $1.15 trillion through the usual appropriations process and $350 billion through the reconciliation process. Byron Callan of Capital Alpha Partners suggested the base budget for 2027 may not clear Congress until spring 2027, six or more months late. That is real uncertainty. But it is not the same as the contracts already signed disappearing.
The Backlog Is the Story
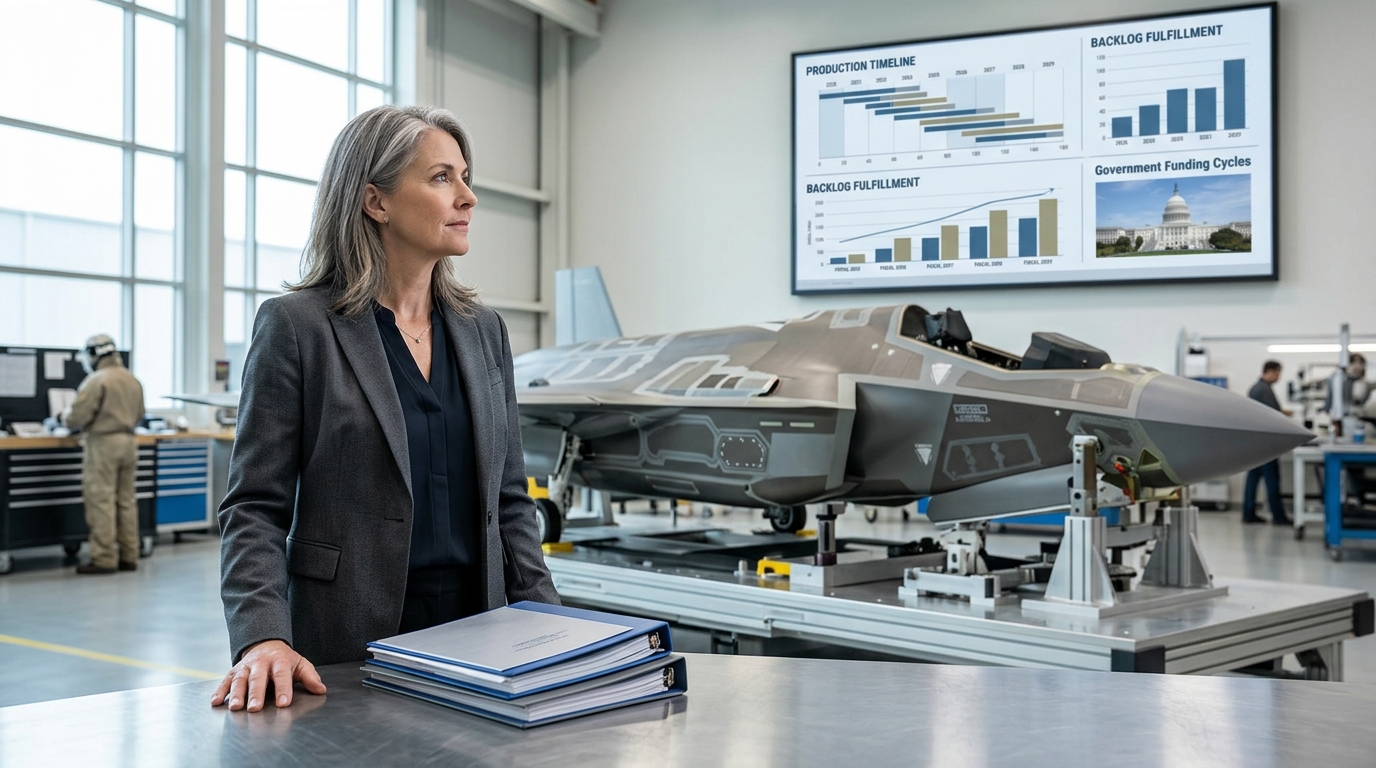
Here is what the selloff has obscured. Lockheed Martin’s backlog, which represents contracted work it has yet to complete, reached a record $292 billion, up 27% from the previous quarter. RTX Chief Financial Officer Neil Mitchill reported another record backlog of $340 billion, up 36% from a year earlier. Northrop Grumman reported $16.4 billion in net awards, bringing its backlog to a record $109.6 billion. These are not projections. They are signed contracts with payment schedules.
With orders piling up, defense contractors are working so hard they cannot meet demand even when operating at full capacity. Yet investors are dumping their stocks. That disconnect between business reality and share price is precisely what creates opportunity for investors with a time horizon longer than the December 11 deadline.
They Proved It Worked in ’76. Then Buried It.
In 1976, Chevron tapped an energy source powerful enough to run a city. No fuel costs. No supply chain. Then they killed it. Unocal and Texaco did the same.
Now one company has spent sixty years perfecting what Big Oil refused to touch. Google locked in a 15-year contract. Bill Gates wrote a $100 million check.
On November 17th, Washington hands it an edge no other energy source gets.
What Is Actually at Risk
The White House asked for $1.5 trillion for defense in fiscal 2027: $1.15 trillion in the normal budget, plus $350 billion through a party-line bill like the 2025 tax law. For Lockheed, what is at stake is primarily the Golden Dome and other add-on priorities tied to that extra $350 billion. The base budget looks more durable. The extras and the timing are not. General Dynamics, with its submarine and shipbuilding exposure that draws bipartisan support, sits at the lower end of that political risk spectrum.
The market’s indifference to signed contracts is not new. The Pentagon awarded seven-year framework deals to triple PAC-3 and quadruple THAAD output, and neither Lockheed nor General Dynamics moved meaningfully on the news.
History offers perspective. After Republicans took the House in 2010, the debt-limit fight produced the 2011 spending caps, and automatic cuts hit the Pentagon in 2013. Defense stocks rose sharply in 2013 anyway, as buybacks and cost cuts beat the budget news. After the 2018 midterms, when Democrats won the House, Lockheed Martin and Northrop Grumman each rose about 1.1% in the next session.
Building a Position Through Uncertainty
A 19% sector derating before the event is a meaningful margin of safety, not a guarantee. The right way to approach a situation like this is in stages. Investors who want exposure to contracted revenue streams and years of funded work ahead of them have genuine reasons to look at LMT, RTX, NOC, GD, and LHX at current levels. They should also size accordingly, because a partial government shutdown remains possible if the parties cannot resolve disputes over spending levels and policy riders before December 11.
Miss These 10 Stocks… Miss the Rally
What are the “Double Engine” stocks for the rest of 2026? Instead of settling for income or growth, these are stocks that deliver both. Our Top 10 Best Stocks to Own in the Second Half of 2026 report includes companies that are the perfect combination of steady payouts and explosive capital appreciation potential – all in one portfolio-ready list. This is how you position ahead of a market tailwind.
The December 11 deadline will produce noise. What it cannot produce is the cancellation of a $292 billion Lockheed backlog or a $340 billion RTX order book. Long-term wealth is built by separating the duration of the headlines from the duration of the underlying business. Right now, those two things are very far apart in defense.
The valuation gap between U.S. defense primes and their European peers adds another dimension to this setup. U.S. defense names remain cheaper than European counterparts even as global budgets approach $2.7 trillion and NATO’s spending floor moves from 2% to 5% of GDP.
Daily Wealth Takeaway
When a sector sells off on an anticipated event, and that event then arrives, the question is never whether the news is bad. It is whether the price already reflects something worse than the reality. The defense sector’s contracted revenue gives patient investors something rare: years of visibility into cash flows that exist independent of what Congress argues about over the next five weeks.