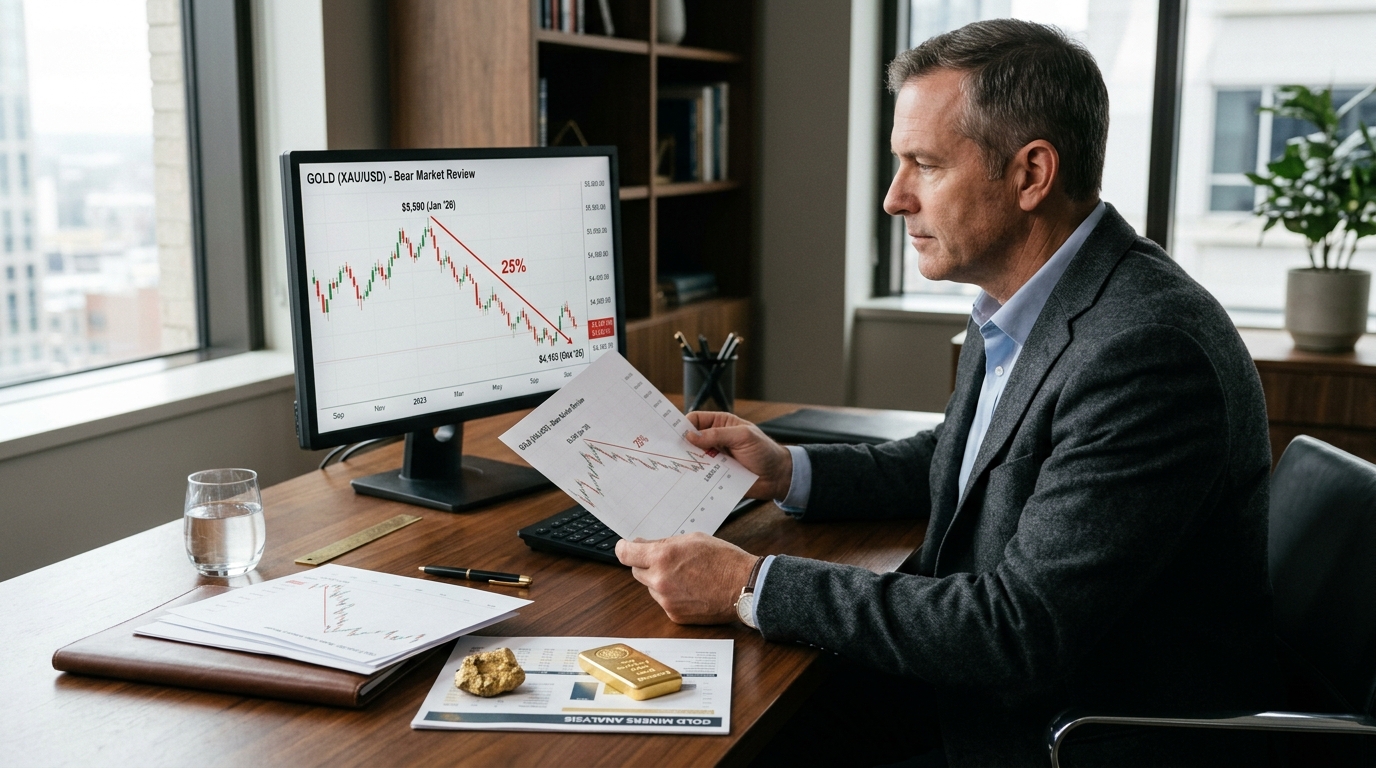
If you bought gold near its January 28, 2026 record of roughly $5,590 per ounce, you are sitting on a loss of about 25%. Gold traded around $4,185 per ounce early on October 12, 2026. That is an uncomfortable place to be, especially when the investment was supposed to protect you from exactly the kind of inflation that headlines keep reminding you is still running above 3%. Before deciding what to do, it helps to understand why this happened and whether the asset that disappointed you is still worth holding.
The Bigger Trend: Real Yields Win Every Time
Gold’s January peak was fueled by one of the fastest bull runs in the metal’s history. After surging roughly 65% in 2025, gold entered 2026 with strong momentum. Then the Federal Reserve kept tightening, and the arithmetic turned brutal.
The mechanism is not complicated. Research by Erb and Harvey puts the correlation between real interest rates and the gold price at about -0.82, when real yields go down, gold tends to go up, and rate hikes are its worst enemy. Rising interest rates also raise the opportunity cost of holding gold, which pays neither dividends nor interest. With the 10-year Treasury note yielding 5.24% as of October 9, and the 30-year around 5.60% on the same date, the competing return on government bonds is the highest in over two decades, making gold’s zero-yield profile a genuine drag.
Inflation being elevated did not save the metal this time, because it is real yields, not nominal ones, that set the gold price. When Treasury yields rise faster than inflation, the real return on bonds climbs and gold suffers. That is precisely what this cycle delivered.
The Investment Case: What Gold Is Actually For
Understanding the loss begins with understanding the role. Gold’s diversification benefit comes from its low long-run correlation with equities and negative relationship with real yields, not from its own return. It is an insurance policy and a tail-risk hedge, not a reliable annual return generator. Investors who sized their gold positions expecting the metal to outperform a 5.24% Treasury were misusing the tool.
Most financial advisors and institutional analysts recommend holding a single-digit percentage allocation to gold, often cited in the 5% to 10% range for diversification. The World Gold Council has published research showing that adding gold to a portfolio has historically improved risk-adjusted results in many portfolio mixes and time windows. A 5% position that drops 25% costs the overall portfolio just over 1%. A 20% position with the same loss costs about 5% of total wealth, and that kind of concentration is a very different risk decision.
If you are overweight gold relative to those benchmarks, the drawdown is your signal to rebalance, not to panic-sell. If you are within the 5% to 10% range, the loss is uncomfortable but within the design of the position.
Building Wealth Around This Idea: The Miner Alternative
Here is the distinction that matters most right now. Even while physical gold has been stuck in a bear market, the companies that dig it out of the ground tell a different story. In the first quarter of 2026, Newmont, Barrick, AngloGold, and Agnico Eagle collectively generated about $6.6 billion in free cash flow. Operating margins per ounce have expanded sharply in 2026’s environment, because production costs have risen far more slowly than realized gold prices did over the past two years.
“Precious metals miners are generating substantial amounts of free cash flow given profit margins of over $2,000 per ounce, and are returning this cash to shareholders through buybacks and dividends,” according to the Gabelli Gold Fund’s co-portfolio manager Chris Mancini. Newmont generated $2.2 billion in free cash flow in the second quarter of 2026 and reported it was on track to achieve full-year guidance.
From those cash flows, miners can fund dividends, unlike non-yield-bearing gold, and gold-miner stocks can also outperform the price of gold as the metal rises in value, because operating and financial leverage can translate into a higher percentage change in free cash flow. The downside leverage runs the other way too: GDX has historically shown much higher volatility than the gold price itself, on the order of low-40% annualized volatility for GDX versus high-teens for gold over long windows. Miners are not a substitute for gold; they are a different bet with a different risk profile. For investors who want gold exposure with an income component and the potential for earnings-driven upside, names like Newmont (NEM), Agnico Eagle (AEM), and Barrick, or the VanEck Gold Miners ETF (GDX), deserve attention at current levels.
Risks to Monitor
The October Federal Reserve meeting is the most immediate catalyst. The case for waiting before adding more gold is that further rate increases could keep pressuring the metal, and the next meeting concludes on October 28, 2026. Bank outlooks for gold into year-end 2026 remain dispersed. Gold supply is not a near-term problem: with mine supply growth generally constrained, even a modest stabilization in investor risk appetite could lay the groundwork for a recovery.
Daily Wealth Takeaway
Every asset has a job. Gold’s job is to diversify, hedge tail risk, and preserve purchasing power across decades, not to outperform a 5.24% Treasury in a rate-hiking cycle. Investors who lost 25% and held a 5% to 10% position suffered a setback. Those who held a 20% position learned the more expensive lesson about why position sizing is as important as the asset itself. Right now, the gold miners are doing what physical gold cannot: paying cash, buying back shares, and generating earnings growth. That combination, in a market where the metal itself is under pressure from real yields, is worth examining closely.