Hi Trader,
Most “gurus” who teach beginners how to trade options start in the wrong place…
Because they immediately launch into complicated concepts like Greeks, spreads, and implied volatility.
And before long, most new traders are completely lost… and move on.
The free guide I want to share with you today takes a different approach.
Instead of overwhelming you with technical details…
It starts with the basics and shows you exactly how options work, why traders use them, and how they can fit into a simple trading plan.
If you’ve ever wanted to understand options but didn’t know where to start…
This is your chance.
Click here and get your free copy now.
To your trading success,
Dave Aquino
Lead Options Trader, Base Camp Trading
Your Bank Dividends Just Got a Smoother Road Ahead
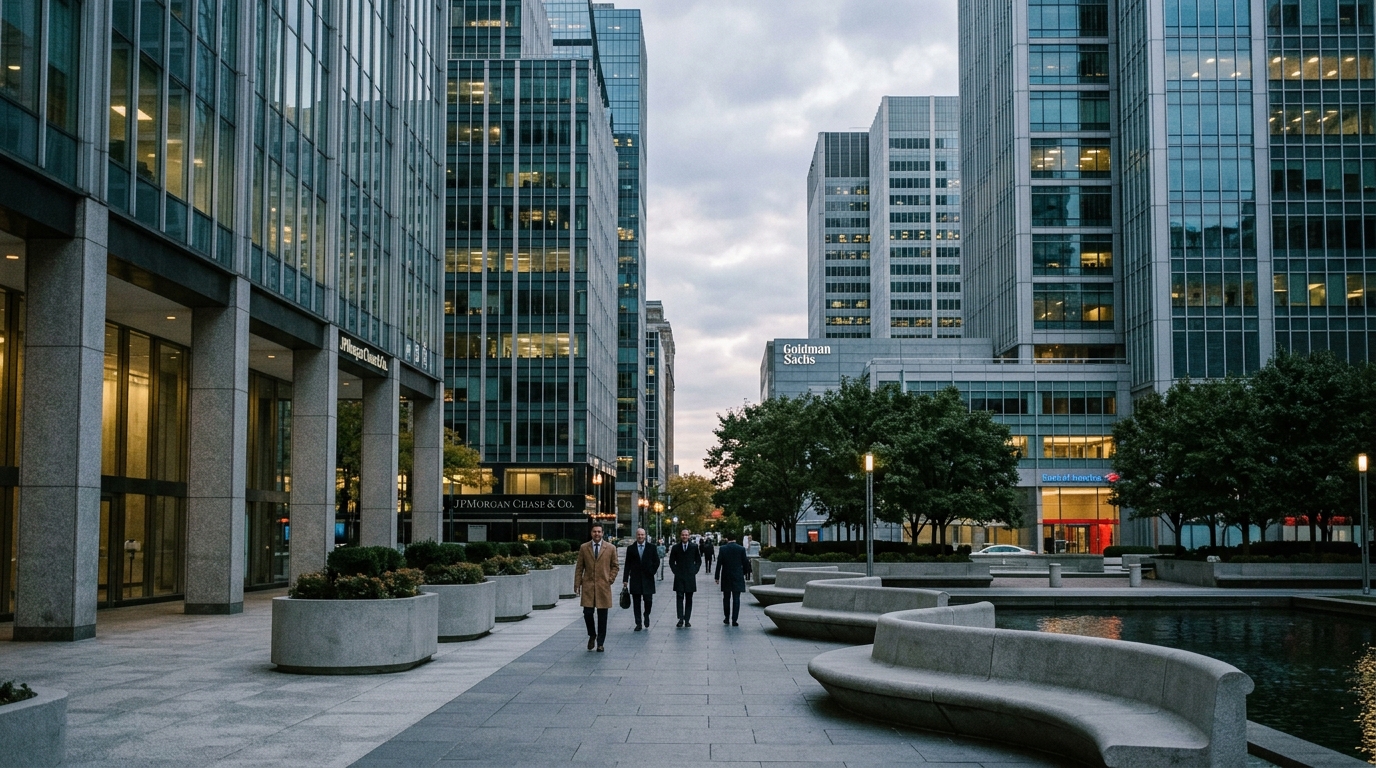
For anyone who owns shares in JPMorgan Chase, Goldman Sachs, Bank of America, Citigroup, Wells Fargo, or Morgan Stanley, the Federal Reserve’s announcement last Tuesday deserves a close read. On September 30, the Fed finalized two rules that reshape how it determines the capital big banks must hold after each annual stress test. The change most relevant to shareholders is straightforward: instead of setting a bank’s stress capital buffer based on a single year’s results, the Fed will now use the average of the two most recent annual tests.
The Fed said the changes are expected to reduce year-over-year volatility in capital requirements by 50% without materially affecting overall bank capital levels. That last part matters enormously. This is not a backdoor capital cut. It is a stabilizer.
Why the Old System Hurt Shareholders
Under the prior framework, a single bad test result could force a bank to hold substantially more capital for the following year, compressing the pool available for dividends and buybacks. A bank “passing” the test simply meant it was not required to raise capital or shrink assets immediately, but banks passed because they now all hold large excess capital as an uncertainty buffer given the randomness of each year’s test results. Shareholders were, in effect, subsidizing that uncertainty buffer through foregone returns.
The Bank Policy Institute noted that for banks that did not see capital increases, that buffer was held for no reason: that capital could have been allocated to fund more loans, and presumably much of it will now be used for share repurchases. That shift in capital allocation is the direct benefit of a smoother regime.
The Broader Regulatory Picture
The stress-test overhaul does not stand alone. Fed Vice Chair for Supervision Michelle Bowman has said the Fed is working on two major capital proposals, the Basel III framework for risk-based capital and a revamp of the additional capital charge applied to globally systemic banks. The direction of travel matters, but the details are not final, and it is not yet clear whether the end result will be a net reduction in required capital for the largest banks. Taken together, these moves represent the most significant recalibration of large-bank capital rules in years, with a clear emphasis on making requirements more transparent and less volatile.
The summer stress tests already showed what banks do when given room. JPMorgan Chase unveiled a new $50 billion share repurchase program and raised its quarterly dividend 10% to $1.65 per share. Goldman Sachs likewise increased its quarterly payout, raising its dividend to $5 per share. Those announcements came before the averaging rule was locked in. With greater capital predictability now improved, boards have a stronger basis for sustaining that momentum.
What to Listen For on October 13
JPMorgan’s next earnings report is due October 13, 2026, with Goldman Sachs, Wells Fargo, and Citigroup reporting the same morning. This earnings season is an early one where management teams can begin to frame how they plan to run capital in light of the Fed’s newly finalized stress test changes, even though the Fed has said the two-year averaging approach will not begin until 2028.
Three questions matter most. First, do executives adjust their stated CET1 targets as the stress capital buffer process becomes less swingy over time? JPMorgan ended June with a CET1 ratio of 14.2%, well above regulatory minimums, giving it clear room to act. Second, do trading-heavy firms like Goldman and Morgan Stanley signal more aggressive buyback timelines, given that the Fed’s final stress-test package now includes two global market shock components each year for firms with large trading books, with the Fed using the shock that produces the largest losses for each firm in its results? Third, listen for any mention of the Basel endgame timeline. If regulators finalize those rules before December, it could change the capital picture heading into 2027.
The Wealth-Building Takeaway
Dividend growth is most durable when it is built on predictable capital generation, not optimistic management guidance. The Fed just made the stress test-related capital planning environment for the largest U.S. banks meaningfully less volatile. That does not guarantee higher payouts, but it removes one of the most persistent obstacles to them. Investors who hold these banks for income have a stronger foundation today than they did a week ago, and the October 13 earnings calls will offer the first real signal of how aggressively banks plan to act on it.