Dear Investor,
I want to ask you a strange question.
What happens when the public turns against the products of a giant industry… but the world still needs the job those products perform?
That is not a theoretical question.
We have watched versions of this story before. For years, tobacco appeared untouchable. It was profitable, familiar and woven into everyday American life.
Then the pressure started building.
Scientific concern. Public scrutiny. Lawsuits. Regulation. A slow but unmistakable change in what consumers would accept.
Tobacco demand could fall because people could stop smoking.
But people cannot simply stop controlling mosquitoes, termites, roaches, ticks and the pests that threaten homes, businesses, food and public health.
That is what makes today’s pesticide story so interesting.
If traditional chemical products face mounting pressure, the need does not go away. The money does not necessarily disappear. It may begin moving toward a different kind of solution.
And quietly – well outside the spotlight of most Wall Street research – one small private company has spent years developing botanical pest-control products designed for this changing market.
That company is Med-X, Inc. It has reserved MXRX for possible use following a successful future Nasdaq listing.
I am not asking you to buy a stock. I am asking you to examine a question before the answer becomes obvious to everyone else:
If pesticides are entering their “tobacco moment,” where could the demand go next?
We prepared a detailed report that follows the entire story – from the historical comparison, to the unavoidable demand for pest control, to the botanical category and the company attempting to build inside it.
The report is long. Deliberately so. It gives you the argument, the counterarguments and the facts you should investigate for yourself.
Click here now to read “Are Pesticides the New Tobacco?”
You may agree with the comparison. You may reject it. Either way, this is a market transition worth understanding.
Sincerely,
The Editors
National Investor Network
P.S. The most consequential changes often look gradual – until suddenly they do not. Read the full investor letter here and decide for yourself whether pest control is approaching one of those moments.
|
UPS Is Paying $5.4 Billion in Dividends With Little Cushion
There are high-yield dividends that reflect a company’s strength, and there are high-yield dividends that reflect a falling stock price. UPS, which reports third-quarter results before the open on Tuesday, October 27, 2026, sits squarely in the second category. The question income investors need answered is whether “6%-plus yield” is an opportunity or a warning dressed in appealing clothing.
Start with the cash. Over the twelve months to June 30, 2026, UPS paid about $5.4 billion of dividends, and management has said it generated about $1.6 billion of free cash flow through the first half of 2026. Management’s own full-year plan calls for roughly $5.5 billion of free cash flow against roughly $5.4 billion in dividends, leaving a margin measured in rounding errors rather than real cushion.
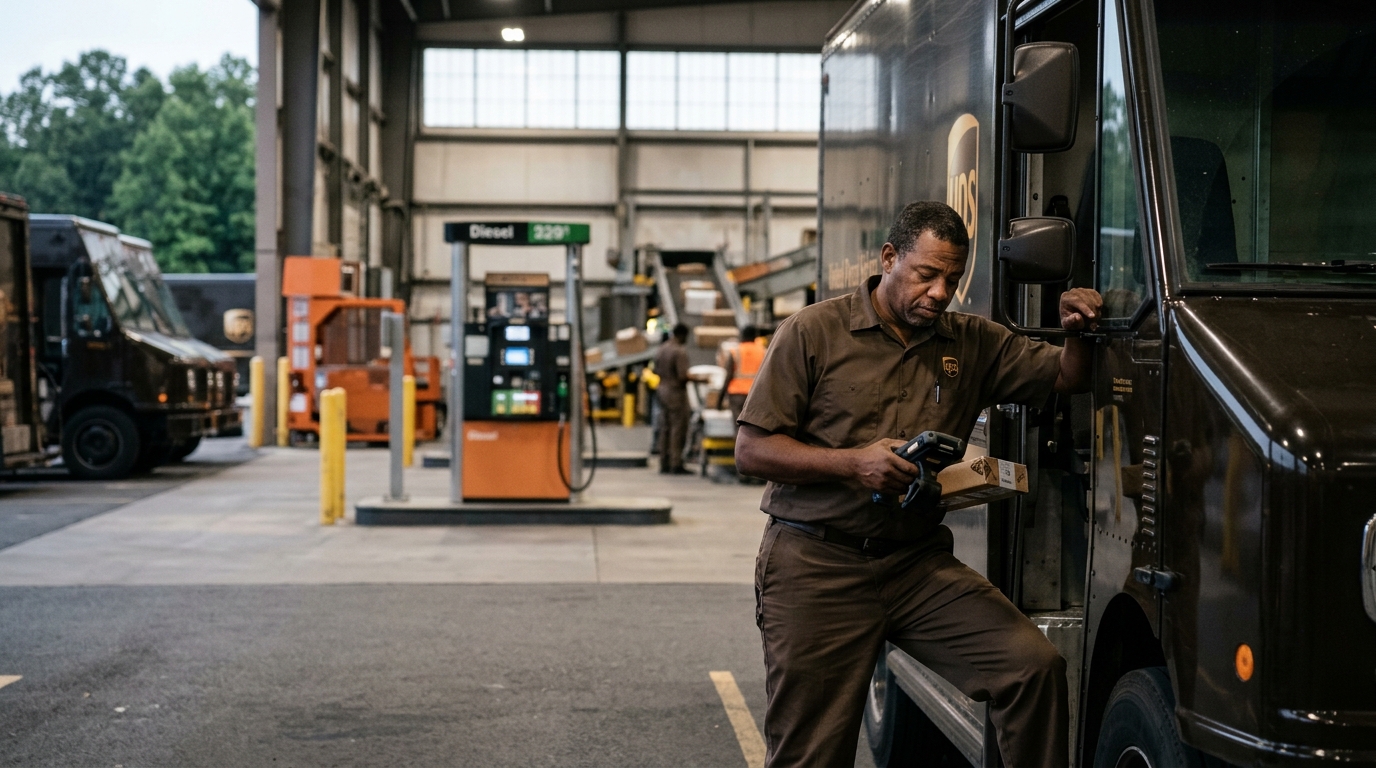
Now add diesel. U.S. on-highway diesel was $6.276 per gallon as of October 19. For a company that moves millions of packages daily in brown trucks, fuel costs of this magnitude are not a line item that gets managed away with a spreadsheet. They compress margins in real time, and Q3 is the first full quarter where that $6-plus per gallon cost sits against a network that UPS has been deliberately downsizing.
UPS’s decision to scale back its relationship with Amazon has kept third-quarter volumes muted. Management has said it is reducing Amazon volume by more than 50% by mid-2026, with CEO Carol Tomé noting that Amazon was not the company’s most profitable customer. The logic is defensible: replace low-margin bulk with higher-yielding small business and enterprise shipments. But the transition leaves the network running below the density that makes the unit economics work, precisely when diesel costs are at their most punishing.
Wall Street is bracing for a mixed picture when UPS reports. One widely cited Wall Street consensus puts expectations at about $1.62 per share on roughly $22.27 billion of revenue for Q3. That estimate implies earnings down year over year. Revenue is expected to grow modestly year over year, but earnings are heading the other direction. That gap matters enormously to dividend investors: revenue growth without earnings growth does not pay the quarterly $1.64.
The back half of 2026 carries an enormous burden. UPS has said it produced about $1.6 billion in free cash flow through June, which means it needs roughly $3.9 billion over the rest of the year to meet its target. That would cover the remaining dividends, but not by much. A meaningful miss on Q3 free cash flow makes the full-year target arithmetically difficult.
UPS names fuel-price volatility and geopolitics, along with tariffs and other trade-policy shifts, among its risks, and either would hit a dividend with no cushion. FedEx, by contrast, has a dividend yield around 1.6%-1.8% and a payout ratio in the mid-20% range. Less income today, more room to maneuver if conditions deteriorate.
None of this automatically means UPS cuts its payout. The quarterly dividend has held at $1.64 for multiple quarters, and management has reaffirmed it at each turn. But the balance-sheet claim here is more conjecture than fact: the “64% debt-to-capital” figure varies by definition and is not something UPS highlights as a single headline metric in its filings.
The honest answer for income investors is this: the dividend is covered on a full-year basis, but only if everything goes right. Diesel above $6, volumes still absorbing the Amazon exit, and analyst EPS estimates that have drifted down are not the conditions under which you want zero margin for error. Tuesday’s report will show how much of the $3.9 billion second-half free cash flow target UPS has already earned, and whether peak season demand shows up the way management expects. Watch free cash flow more carefully than earnings per share. That single number determines whether the 6%-plus yield is income or an IOU.