October 9, 2026
Bonus Content: UK Card Defaults Have Risen for Six Straight Quarters
SPONSORED CONTENT
“Six Banks Have Failed in 2026. Would You Know If Yours Were Next?”
During the first year of the 2008 financial crisis, 25 FDIC-insured U.S. banks failed
On September 25, regulators closed Nano Banc in California. It was the sixth U.S. bank to fail this year, and the largest, with about $736 million in assets. The six failures together represented roughly $1.4 billion in combined assets, making 2026 the highest bank-failure count in over a decade.
Six failures may not sound like many. But it’s the most in any year since 2017, and triple the two failures recorded in each of 2024 and 2025. Most of this year’s failed banks were small. That’s often how stress shows up first: in the weakest institutions, before it reaches the larger ones.
|
The pressures behind them haven’t gone away. Ten-year Treasury yields recently climbed to around 5.3%, and when yields rise, the bonds banks already own lose value. Commercial real estate loans are coming due at much higher rates. That’s the same combination that brought down Silicon Valley Bank in 2023, when losses on its bond portfolio sparked a run that emptied the bank in about two days.
Bank stress can look manageable, until confidence disappears.
FDIC insurance covers deposits up to $250,000 per depositor, per insured bank, per ownership category. But the fund behind that promise held about $161 billion as of mid-2026, roughly 1.5 cents for every insured dollar. It’s a backstop built on confidence, not a dollar-for-dollar reserve.
Nobody can predict which bank fails next, and you should be wary of anyone who claims they can. What you can do is understand your exposure. If your IRA, 401(k), TSP or 403(b) is held entirely in bank deposits, bonds and other paper assets, every dollar of your retirement depends on the strength of that system.
The free Precious Metals Retirement Guide covers:
✔ What FDIC insurance does, and doesn’t, protect in the accounts you hold today.
✔ How physical gold and silver have behaved during past periods of banking and financial stress.
✔ How you may be eligible to move a portion of an existing retirement account into physical metals, generally without a taxable distribution when structured correctly.
UK Card Defaults Have Risen for Six Straight Quarters
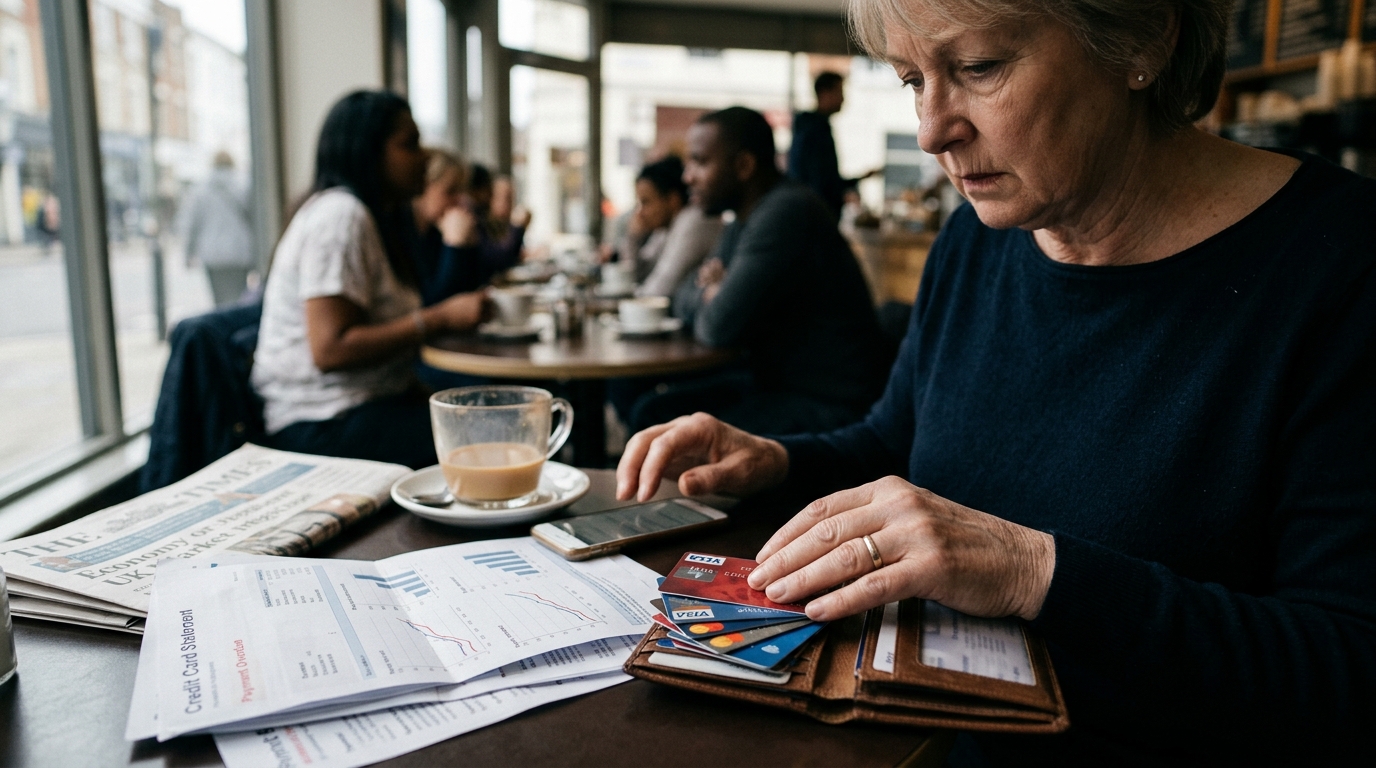
Six consecutive quarters. Eighteen months of unbroken deterioration in UK credit card default rates. The streak, last seen during the 2008-09 financial crisis, now matches the kind of sustained household stress that preceded a generational market reckoning. The Bank of England published these findings on October 8, 2026, and the timing demands attention from anyone carrying revolving debt or invested in lenders exposed to UK consumers.
What the Survey Actually Shows
The Bank of England’s latest Credit Conditions Survey showed a net percentage balance of +25.7 for credit card default rates in the three months to end-August 2026. That is not a rounding error. It is a lopsided consensus among the institutions closest to household balance sheets.
The survey was conducted between August 17 and September 4, and it does not capture the impact of developments after that period. The survey also showed lenders expected credit card default rates to rise again in the three months to end-November 2026. Lenders, in other words, already expect more pain before the data can even reflect it.
The divergence between unsecured and secured lending sharpens the picture. Lenders reported a slight decline in secured-loan default rates in the three months to end-August 2026, and expected secured-loan default rates to be broadly unchanged in the three months to end-November. The stress is concentrated precisely where interest rates hit hardest and where borrowers have the least collateral.
The Cost of Carrying Revolving Debt Into Winter
Banks and building societies expect defaults on credit card lending to rise further in the three months to end-November 2026, suggesting that the strain on household finances could intensify as higher energy bills, inflation and borrowing costs collide with the seasonal increase in consumer spending.
A separate Bank of England Money and Credit release showed net borrowing of consumer credit by individuals rose by £2.5 billion in August 2026, with £1.2 billion of that on credit cards. Borrowing more while default rates climb is not a sustainable position. It is what a squeeze looks like from the inside, before it shows up in lenders’ income statements.
With the Autumn Budget looming and Bank of England interest rate increases potentially on the horizon, households may remain cautious about making major financial commitments, yet the data suggests many are already past the point of caution and into the territory of distress.
The Wealth Lesson
This survey is not simply a commentary on British consumers. It is a live case study in what happens when households allow revolving balances to compound through a rate cycle. Revolving credit card debt, the kind where only a minimum payment gets made each month, becomes a wealth-destroying mechanism when rates stay elevated. The Bank of England’s survey shows that at scale, those balances cannot be serviced indefinitely.
For investors, the practical implication runs in two directions. Shares in UK retail lenders including Lloyds, NatWest, Barclays, HSBC, and Nationwide carry measurable exposure to deteriorating unsecured credit quality. The six-quarter streak suggests provisioning requirements are not behind us. For individual readers still carrying a revolving credit card balance, the same logic applies with more urgency: the cost of waiting to pay it down is rising each quarter the Bank of England’s survey confirms what lenders already expect.
Wealth is eroded incrementally, long before a default ever appears on a statement. That is the signal buried in October 8’s data.