September 19, 2026
Bonus Content: Costco’s Membership Engine Is the Real Reason to Own It
Dear Reader,
In 1998, a 27-year-old Elon Musk set out to redesign how the U.S. dollar moves.
That effort was interrupted before it could launch.
His PayPal co-founders removed him from the project, and he spent the next two decades building Tesla, SpaceX, and xAI instead.
Accumulating a degree of capital and institutional reach without modern precedent.
Now that original thesis is back on the table.
He is moving to reboot the architecture of the U.S. dollar — with reported alignment from the White House, Congress, and the U.S. Treasury.
If the initiative scales, analysts tracking it believe the underlying technology could represent a larger market event than Tesla and SpaceX combined.
For investors positioned early, this may shape up as one of the more asymmetric opportunities of the decade.
Regards,
Ian King
Chief Strategist, Strategic Fortunes
Costco’s Membership Engine Is the Real Reason to Own It
Costco reports fiscal fourth-quarter results after the close this Thursday, September 24, 2026, and the conversation on every financial desk is about the earnings beat-or-miss and whether the stock moves 1% or 4%. That is the wrong conversation for investors who own Costco as a long-term wealth-building position.
The number that actually matters Thursday is not revenue or adjusted EPS. It is the membership renewal rate.
What Analysts Expect
Wall Street expects Costco to report revenue of $94.85 billion, up 10% from $86.16 billion last year, with adjusted earnings per share rising 12% year-over-year to $6.55. Costco has been mixed versus analysts’ EPS estimates in recent quarters. Oppenheimer’s Rupesh Parikh reiterated an Outperform rating and maintained a $1,160 price target heading into the report. UBS analyst Michael Lasser also remains bullish, keeping his Buy rating and a $1,275 price target, implying roughly 42% upside from recent levels.
The broader consumer backdrop is genuinely mixed. August retail sales surged 1.2%, exceeding the consensus expectation of 0.8%. A key GDP-linked measure of spending rose 1.4%, the largest increase in five months. That headline strength still masks a consumer under real strain. The University of Michigan’s consumer sentiment index fell to 51.0 in August from 55.2 in July on elevated inflation concerns. The same pressures are showing up in Costco’s own aisles: a case of Kirkland Signature full-synthetic motor oil has nearly doubled in price, and the company has introduced purchase limits on its motor oil as supply tightens globally.
The Membership Engine
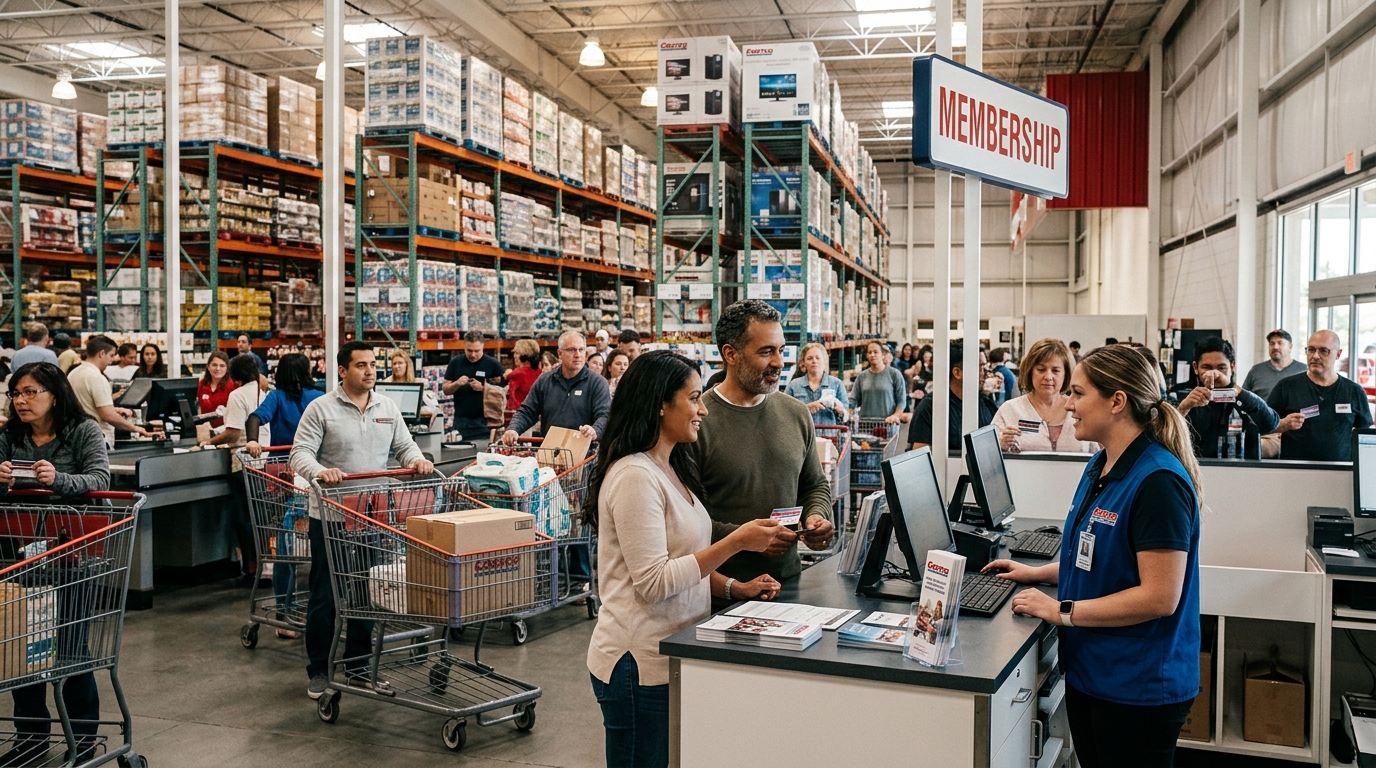
Here is what separates Costco from every other retailer in this environment. Its profit model does not depend on wide merchandise margins. It depends on members paying annual fees and renewing them, year after year, at extraordinary rates.
During the first 24 weeks of fiscal 2026, membership fees contributed $2.684 billion. In the same period, merchandise sales on $134.220 billion of net sales generated $14.991 billion in gross margin before selling, general and administrative costs. The fee stream is, in effect, the earnings stabilizer investors should care about most.
The U.S. and Canada renewal rate stood at 92.2% at fiscal Q3 2026 quarter-end, up 10 basis points sequentially, while the worldwide rate held at 89.7%. Those figures need to hold or improve Thursday. When Costco raised its Gold Star fee from $60 to $65 and its Executive fee from $120 to $130 effective September 1, 2024, the early signal from management was that renewal rates remained resilient. That is a strong demonstration of pricing power and member loyalty, and it leaves the door open for another fee increase well before the next seven-year cycle.
The way membership fees drive Costco’s bottom line means the entire company can grow earnings faster by growing membership fees than by selling more merchandise. Ten percent annual revenue growth at this scale, with membership income compounding on top of it, is the foundation of Costco’s long-term wealth-building case.
Risks to Monitor
UBS analyst Lasser noted that the retail environment is more complex and less straightforward for Costco than it has been in recent years. Costco shares have fallen about 18% from their mid-May 2026 record high, which brings valuation into sharper focus. The stock has been trading at a premium multiple versus many retailers, which requires continued earnings execution to justify. Any deceleration in renewal rates, or disappointing commentary on tariff-related cost pressures, could extend the pullback.
The Wealth Takeaway
Costco’s Q4 report will generate short-term noise. What it will not change is the underlying case for patient holders: a near-indestructible membership model, durable revenue growth, and a fee engine that produces profits most retailers cannot approach. Investors who focus Thursday on whether the membership renewal rate holds above 90% in the U.S. and Canada are asking the right question. The rest is quarterly weather.