On November 10, On Holding reported the kind of quarter most consumer brands would envy: net sales grew 17.8% at constant currency to CHF 931.4 million. The stock fell 7.5% anyway. That gap between the business and the share price is where the opportunity lives.
The sell-off was not irrational. Inventory increased to CHF 495.7 million, up 30.2% year-over-year, keeping alive the concern that future markdowns may be needed if demand slows. In a promotional retail environment, inventory builds get punished fast. But the market is reading the wrong line.
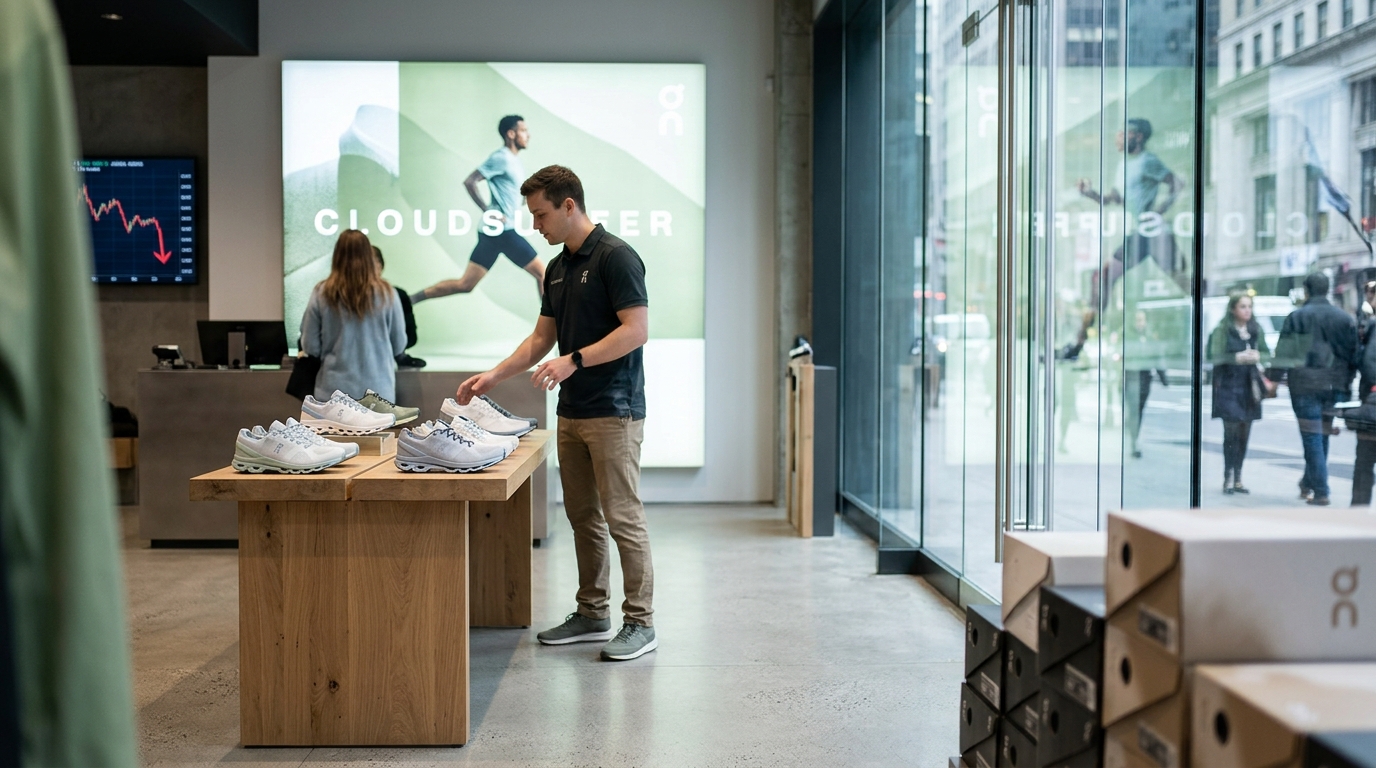
The number that matters most arrived after the quarter ended. In its first week, the Cloudsurfer 3 sold through at more than four times the rate the Cloudsurfer 2 did in its launch week. That is not a launch bump. That is a signal about whether On’s new sensation-based franchise architecture and SURREAL superfoam are resonating with the technical running market, which is precisely the channel the brand needs to protect its premium positioning.
The performance-running channel, where technical credibility is earned, had weakened while lifestyle sales continued monetizing that credibility. Losing specialist runners is more consequential than their immediate revenue share suggests. A premium athletic brand must repeatedly demonstrate that its shoes deserve to exist beyond fashion. The Cloudsurfer 3 is the first hard evidence that On can do that.
The performance-running channel is a zero-sum competition. Nike’s own turnaround depends on reclaiming the technical running credibility it ceded to brands like On over the past three years.
Wholesale partners noticed. On said the strong sell-through signal prompted larger-box partners to increase their Spring 2027 orders. That is a forward order book strengthening in real time, not a projection. The footwear maker expanded gross margins by protecting full-price selling despite promotional pressure across the broader apparel market, and On reaffirmed its 2026 sales growth target in the low-20% range at constant currency and raised its gross margin outlook to around 66% excluding U.S. tariff refunds.
Analyst conviction held through the decline. Twenty-five of 31 tracking firms rate the stock Buy or Strong Buy, with Cantor Fitzgerald initiating coverage at a $46 price target. KeyBanc Capital Markets analyst Ashley Owens maintained an Overweight rating and raised the price target from $37 to $42. Shares are down about 26% year to date and about 32% below their 52-week high of $51.08.
The real question is not whether the Cloudsurfer 3 had a strong launch week. It did. The question is whether January’s broader rollout sustains full-price sell-through beyond the run-specialty exclusivity window. The January rollout has to keep the strong launch sell-through going at full price, fourth-quarter growth has to accelerate as forecast, and the underlying gross margin has to stay near the raised 66% outlook despite tariff exposure. Those are the three checkpoints that determine whether this entry point was real or just cheap for a reason.
The wealth-building lesson here is straightforward: when a stock drops on record margins and a product launch with demonstrably stronger demand than its predecessor, the market is usually pricing a risk, not a failure. Know which one you are buying.