October 14, 2026
The ZO Skin Health deal shows where durable consumer spending is hiding, and which public companies sit closest to the opportunity.
Blackstone does not sell things cheaply, and it certainly does not sell them without a reason. So when the firm agreed this week to hand over ZO Skin Health to Swiss dermatology giant Galderma for $1.5 billion in cash, the price tag deserved a second look.
Don’t sell your shares to him on Friday afternoon…
Every Friday afternoon like clockwork, a legendary trader scoops up shares knowing after-hours breaking news will have traders desperate on Monday morning to buy back from him for 5X… 10X… or even 100X what they sold for.
All the while he gets to collect as much as $9,518 OR MORE just for holding shares over the weekend.
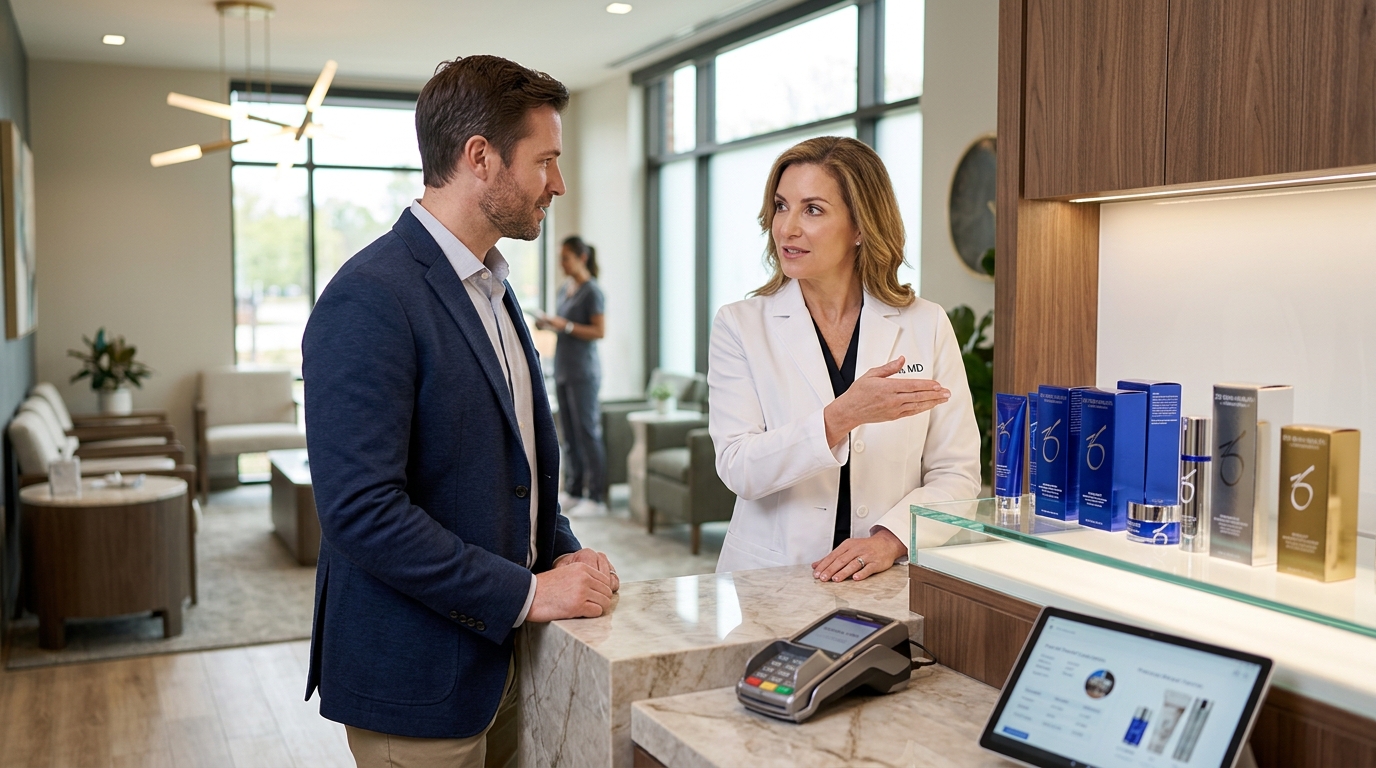
Galderma confirmed on Wednesday, October 14, 2026 that it had agreed to buy ZO Skin Health, a physician-dispensed skincare brand owned by Blackstone, for an enterprise value of $1.5 billion in cash, expanding its dermatological skincare business as competition grows for clinically backed brands. The transaction is expected to close in the fourth quarter of 2026 or early 2027, subject to regulatory approvals.
The Bigger Trend
The deal is not really about one brand. It is about where consumer spending refuses to compress even when budgets tighten elsewhere. Physician-dispensed skincare, sold through dermatologists and medical spas rather than department store counters, has carved out a defensible corner of the beauty market precisely because it is anchored to clinical credibility. Patients trust what a doctor recommends. That trust commands a price premium, and it tends to hold up.
In the U.S., SkinCeuticals, ZO Skin Health, and SkinBetter Science continued to command a significant share of medical care provider sales in the first half of 2026. E-commerce grew at a strong double-digit rate in the first half of 2026, outpacing the medical care provider channel, suggesting these brands are crossing over from the clinic into the home without losing their authority.
Blackstone recognized this dynamic years ago when it backed ZO alongside the founding Obagi family. Founded by dermatologist Dr. Zein Obagi and headquartered in Irvine, California, ZO Skin Health has been a reference name in clinically backed professional skincare for more than two decades, with a portfolio spanning over 40 products sold through more than 16,500 physician, medical spa, and online accounts across more than 40 countries. ZO recorded net sales of about $330 million in the 12 months to June 2026. At 4.5 times trailing revenue, Galderma paid a premium that reflects exactly what it is buying: a brand that earns a physician’s endorsement every time it is dispensed.
5 Rules. Plain English. Zero Jargon.
You don’t need a psychology degree to stop revenge trading.
You need a few simple rules, set ahead of time, that you follow no matter how the day is going.
That’s what you’ll get in How To Stop Revenge Trading in 5 Steps. Plain English. Rules you can use tomorrow morning.
The Investment Case
The deal will bring ZO under the same roof as Galderma’s Cetaphil and Alastin brands. Galderma is also the maker of the Dysport neurotoxin and Restylane dermal fillers, and L’Oréal holds a 20% stake in the company. That portfolio depth matters. When a patient walks into a dermatologist’s office, Galderma now touches nearly every commercial moment: the injectable, the filler, the post-procedure skincare regimen, and the daily maintenance routine at home.
The company expects the deal to be neutral to core earnings per share in the first full year after closing and slightly dilutive to its core EBITDA margin in 2027, with margins broadly in line with the group average from 2028, as it plans to increase commercial investment in the first year of ownership and aims for renewed growth from the second year. That is a measured rollout, not a panic buy.
Galderma trades on the SIX Swiss Exchange under the ticker GALD and is accessible to U.S. investors via the OTC market as GALDY. The company is Switzerland-based and, as of October 13, 2026, carried a market capitalization of about CHF 39.0 billion. For investors who cannot access it directly, the competitive map is worth understanding.
Building Wealth Around This Idea
The publicly traded names closest to this theme are AbbVie (NYSE: ABBV) and Evolus (Nasdaq: EOLS). The Allergan Aesthetics portfolio, an AbbVie division, rebounded from weakness that defined 2025, with global BOTOX Cosmetic net revenues reaching $668 million in Q1 2026, up 20.2% on a reported basis. Skin quality is increasingly viewed as the foundation of aesthetic care according to AbbVie’s own consumer research across more than 12,000 respondents, and its SkinMedica line competes directly in the physician-dispensed lane where ZO has thrived.
Evolus sits further down the market cap spectrum but is gaining ground in neurotoxins, the injectables category that feeds patients into the broader skincare ecosystem. As more clinics layer toxin treatments with adjunct skincare protocols, smaller players that serve those clinics well get pulled along.
Risks to Monitor
Galderma is paying for growth it has not yet generated. ZO’s revenue has been relatively flat, and the company acknowledges it will invest heavily in year one before margins normalize. Integration of a founder-built brand into a large Swiss corporation always carries cultural friction, and Dr. Obagi’s name is inseparable from ZO’s clinical identity. The transition of physician loyalty from founder to parent company is never guaranteed.
Broader macro risk is real but manageable. This growth trajectory is supported by advancing technologies in non-surgical procedures, rising disposable incomes, and a cultural shift toward preventative skin health and anti-aging solutions. Those tailwinds exist, but they can moderate quickly if consumer confidence cracks.
Record-High Copper Ignites District-Scale Discovery Below $2
Copper has blasted to all-time highs as AI data centers, electrification, and grid expansion drive demand for the strategic metal. One small-cap Canadian copper company trading below $2 is unlocking a historic Yukon copper belt that was never explored as a unified system. High-grade copper is already confirmed at the flagship, multiple opportunities are advancing across the belt, and drilling is accelerating with multiple rigs turning.
See what the drills are targeting next – before the next copper-gold results hit.
The valuation backdrop for this category is worth framing against the broader sector. Healthcare’s 20% discount to the S&P 500 and three straight years of underperformance set the floor from which premium aesthetics names are now recovering.
Daily Wealth Takeaway
Blackstone built a $1.5 billion exit by owning something consumers keep buying through recessions: the endorsement of a doctor. That is the structural insight worth keeping. When private equity consistently finds an exit at a premium in one category, it signals durable demand. Physician-dispensed skincare is now clearly in that category, and the public companies sitting inside that ecosystem deserve a place on every investor’s watchlist.