October 7, 2026
Bonus Content: Tokenized Luxury Investments Can Lock You Out When You Need Out Most
If you have $25,000 or more in the bank or a retirement account, read this now!
Dedollarize News
October 26: Four Systems. One Deadline.
Click Here to See Why October 26 Matters
Who gets a say in the financial systems handling YOUR money?
On October 26, 2026, public-comment windows close on four federal information collections covering bank deposits, financial customer-data security, securities-market activity and institutional trade settlement.
Four proceedings. One deadline.
Before that deadline, watch what former Goldman Sachs president Gary Cohn said at the public FDIC meeting on November 9, 2022:
“I almost think you’d scare the public if you put this out.”
They were discussing how to explain the resolution of major financial institutions while maintaining public confidence.
The meeting was public. The words are in the transcript.
6,714 matching bank-branch closing records since the day he said it.
That is the result reported in our FDIC BankFind search from November 9, 2022 through September 30, 2026, using data labeled September 29, 2026. These are branch-closing records, not failed banks.
Watch Gary Cohn’s Words and See the Live Branch-Closing Counter.
And when the FDIC recently invited comments on renewing its branch-deposit survey, it received ZERO.
America’s financial infrastructure is changing in plain sight. How closely are you watching?
Watch the exchange, follow the live branch-closing counter and read about the four proceedings before their comment windows close.
Click Here to Watch Before October 26.
Bill Brocius
Author of The Vanishing Dollar and Digital Dollar Exposed
Dedollarize News
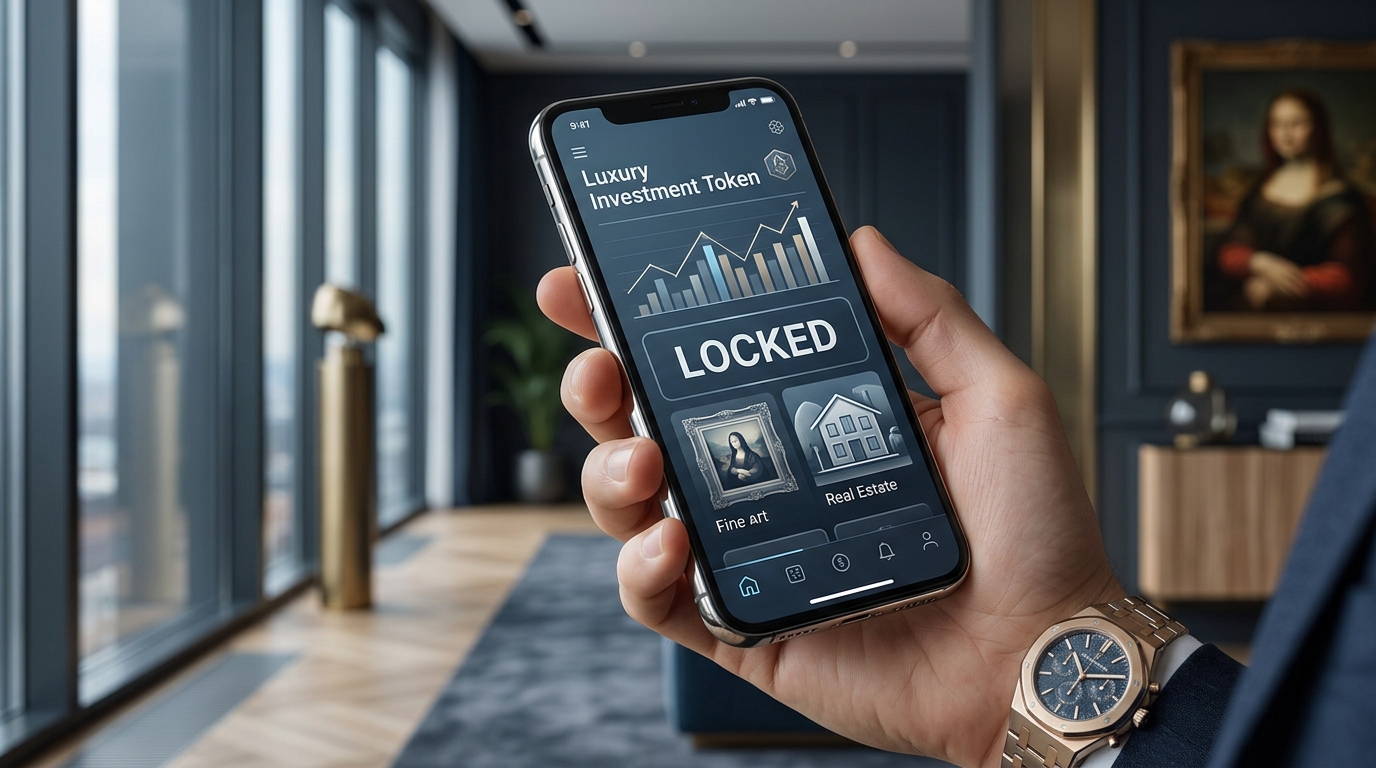
Tokenized Luxury Investments Can Lock You Out When You Need Out Most
The pitch is elegant: own a fraction of a Basquiat or a Miami penthouse for a few hundred dollars, collect your proportional returns, and sell whenever you like. What the pitch omits is the exit clause.
Fractional ownership of fine art and luxury collectibles exists through platforms like Masterworks. In practice, the investment is typically a securities offering, and the secondary market may be limited and inconsistent. That last phrase deserves more weight than it typically gets in a bull market.
The core problem is structural, not cyclical. Secondary-market liquidity can be thin enough that exiting a meaningful position may require accepting a steep discount, and pricing can be driven more by who is willing to trade than by the most recent underlying valuation. In calm conditions, that cost is tolerable. In a contracting market, it becomes a trap. Sellers arrive in volume precisely when buyers vanish, and the spread between what a token is theoretically worth and what someone will pay for it can widen to levels that make the underlying asset’s own decline look modest.
In thin markets, or during a downturn in the underlying asset class, selling a fraction may be difficult or only possible at a steep discount. Community members who tried fractional real estate platforms during market slowdowns found secondary markets much less liquid than advertised.
The RealT episode sharpened this lesson. In late June 2025, Detroit filed what city officials described as its largest nuisance abatement lawsuit, tied to 408 properties connected to RealT. In May 2026, a Detroit judge granted a temporary restraining order that barred RealT from evicting tenants or collecting rent on those properties until compliance issues were addressed. In July 2026, RealT said on a community call that it planned a voluntary liquidation of its Detroit LLCs. The episode illustrates a fundamental tension: blockchain infrastructure can make ownership transfer seamless, but it cannot solve property management, regulatory compliance, or physical maintenance. Tokens are only as good as the entity and operations behind them.
Fine art compounds the problem because the underlying asset has no cash flow to anchor its value. A tokenized Richter generates no rental income. During broad market contractions, luxury art can fall as collectors retrench, and the small pool of credible buyers for a specific work shrinks further. A fractional token representing a sliver of that work has an even smaller buyer pool on the secondary market.
Token prices can move independently of the underlying property or asset value when marketplace liquidity is thin. In practice, this means retail investors can hold a token that says one price while the only bids in the market reflect something materially lower.
None of this means the space has no future. Treating a tokenized luxury position as a small allocation of money you will not need for at least three years is the honest framing. The problem is that most retail platforms market these instruments as democratized liquidity, not as illiquid alternatives. When the next broad contraction hits, that distinction will matter more than any yield projection on a marketing page.