September 21, 2026
Private credit was sold as steady income. New data says more borrowers are failing to pay. Here is what to check before you trust the yield.
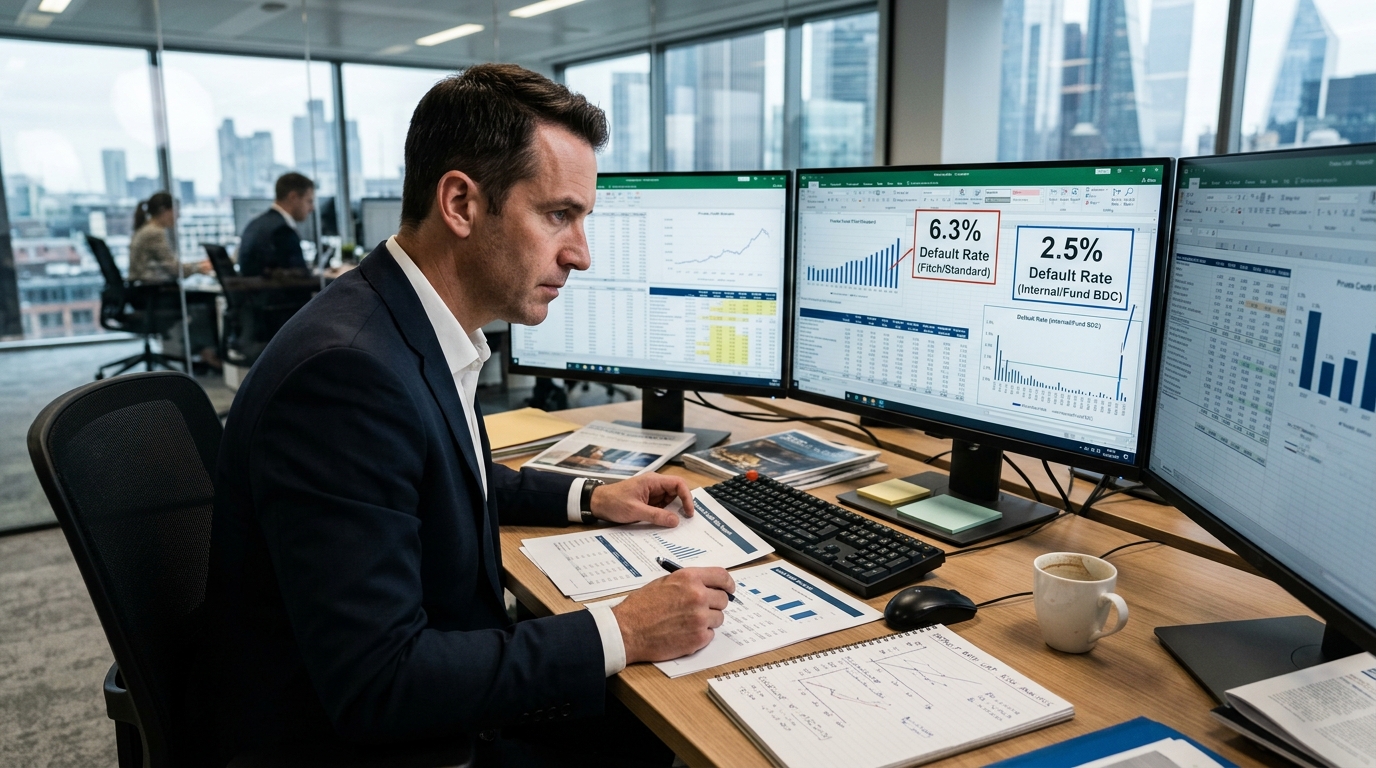
The same $2 trillion market. Completely different numbers. Either private credit has a serious default problem, or barely one at all, it all depends on who is counting. That disparity is not a footnote. For the growing number of individual investors who were sold private credit funds as steady, bond-like income, it is the central question worth understanding right now.
The AI Boom’s Most Profitable “Tollbooth” Stock?
A little-known company is quietly building what may be the closest thing to a virtual monopoly the AI era has ever seen.
Whitney Tilson – the man CNBC calls “The Prophet” – calls it the world’s most profitable tollbooth. One billionaire put more than half his $9 billion fund into it.
Right now it’s trading at a rare discount…the same kind that’s previously turned $10,000 into $55,000…in just over 12 months.
Fitch Ratings put the trailing 12-month default rate at 6.3% through August 2026, edging up from July’s 6.1% and setting a new high. Meanwhile, Proskauer’s Private Credit Default Index, which tracks senior secured and unitranche loans, revealed a default rate of 2.51% for the second quarter of 2026.
The gap is not a data error. It is a definitional one, sitting at the center of why regulators have been writing about an asset class that barely existed at scale fifteen years ago. Fitch’s count blends a model-based series tracking credit opinions used in middle-market CLOs with a privately monitored ratings series often used by insurers. Proskauer’s index captures only senior secured and unitranche loans from a legal practice that advises lenders directly. Each measure is internally consistent. Neither tells the complete story.
The definitional question matters because of how distressed restructurings are counted. Moody’s analysis suggests the private credit default rate in 2025 likely ranged between 1.6% and 4.7%, depending on whether distressed exchanges are included, with such restructurings accounting for approximately 65% of all defaults that year. A borrower that negotiates a maturity extension under pressure may never appear in a fund’s reported default tally, yet the economic impairment is real.
You’re Being LIED To About The Iran War
Forget EVERYTHING you’ve heard about the Iran war.
Especially the reasons why we’re bombing the country.
The trajectory matters even more than the level. Morgan Stanley has warned that default rates in private credit direct lending could surge to 8%, well above the historical average, with pressure concentrated in sectors vulnerable to AI disruption, such as software. That is cold comfort if your fund is concentrated in software.
For investors holding positions in publicly traded BDCs such as Ares Capital (ARCC), Blackstone Secured Lending (BXSL), Blue Owl Capital (OBDC), or FS KKR Capital (FSK), there are three things worth examining now. First, payment-in-kind income. The Boston Fed documented a steady increase in PIK usage since early 2022, with the share of BDC loans using PIK rising from about 6% to nearly 10% by early 2026. PIK means the borrower is adding unpaid interest to the loan balance rather than paying cash. Rising PIK is a warning sign, not income.
Second, sector concentration. Fitch’s data shows a wide spread across sectors, with technology software at 0.6% in August 2026 while healthcare providers were at 9.9%. Healthcare providers also had the most unique defaulters in the trailing-year period, totaling 18, alongside that 9.9% default rate. Any fund with heavy healthcare or industrial exposure faces a fundamentally different risk profile than one concentrated in technology lending.
5 Little-Known Stocks Behind Today’s Defense Tech Shift
Behind the headlines, a major transformation is underway.
Modern warfare is being driven by AI, autonomous systems, and next generation technology. A handful of lesser known companies are helping power this shift.
This report uncovers five stocks quietly playing a critical role in the future of defense.
Third, the quality of what you own. FSK reported that KKR agreed in May 2026 to purchase $150 million of convertible preferred stock, and the company also authorized up to $300 million in share repurchases. That is a very different animal from ARCC, which is primarily oriented toward senior secured lending and emphasizes first-lien positions across a broadly diversified portfolio.
The wealth-building lesson here is not that private credit is broken. It is that a category return obscures enormous manager-level dispersion. For investors accessing private credit through BDCs or interval funds, manager-level diligence matters more than category-level allocation. Look at the SEC filings. Compare PIK income percentages across quarters. Ask whether the fund’s sector weights match the sectors where defaults are rising. The answer to those questions is more useful than any single default rate, regardless of who is counting.