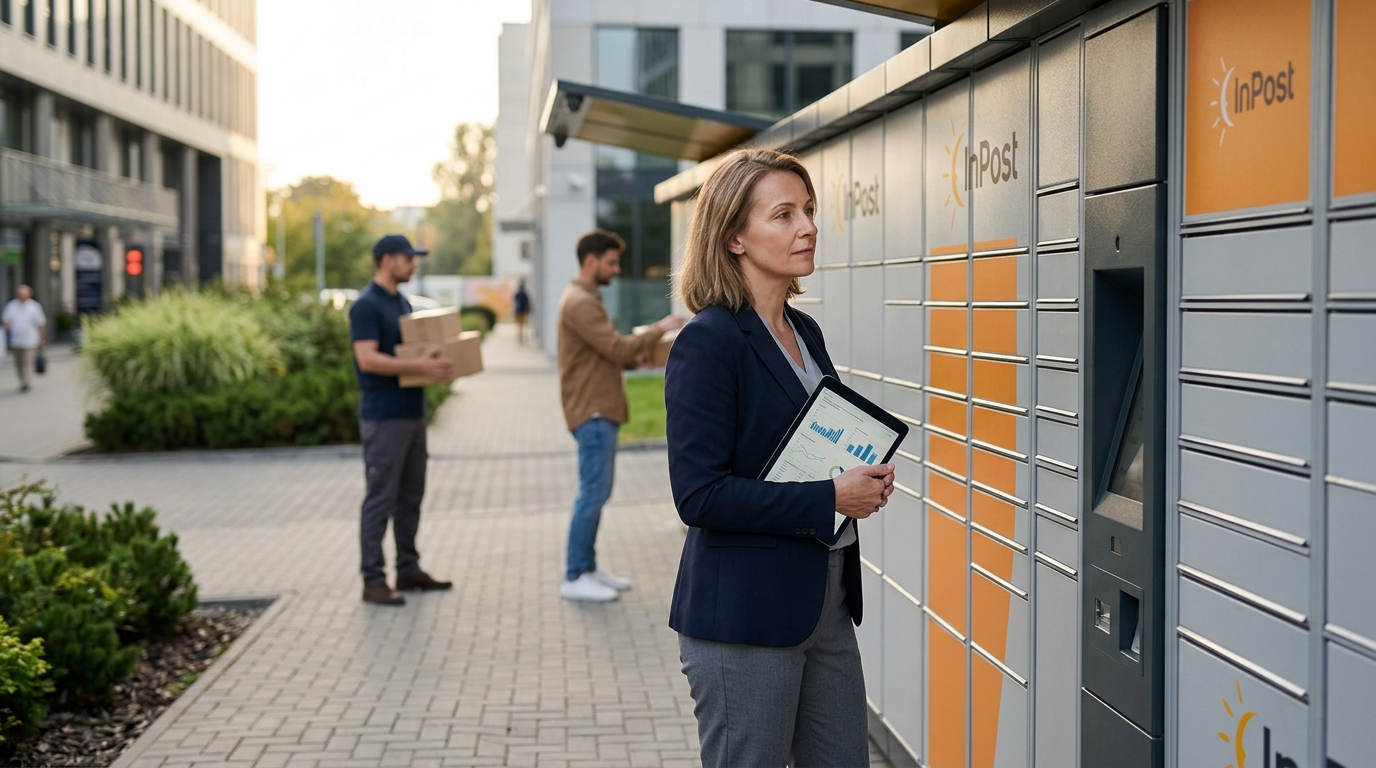
The consortium cleared the minimum 80% acceptance threshold for its €7.8 billion (about $8.9 billion) offer, with 89.81% of shares tendered by the Friday, September 18, 2026 deadline. The deal is done. InPost will leave public trading. And FedEx shareholders are now holding a 37% stake in a business that had better earn its place in the portfolio.
This is not a flashy acquisition. InPost operates across nine countries including Poland and has one of Europe’s largest networks of automated parcel lockers. The company ended the second quarter of 2026 with 68,925 automated parcel machines, 29% more than a year earlier. That kind of physical density does not come cheap to replicate, which is precisely why FedEx wanted it rather than built it.
The Arithmetic FedEx Must Beat
FedEx is acquiring a 37% stake for about $2.6 billion, establishing arm’s-length operating partnerships giving it access to InPost’s large network of parcel lockers in Western Europe and lowering its cost to serve compared to residential door delivery. The €15.60-per-share offer is financed in part by €4.95 billion in committed debt. That leverage is sitting inside the new holding company, not on FedEx’s balance sheet directly, but investors should not pretend it is invisible.
InPost reported revenue of PLN 8.04 billion for the first half of 2026. A €7.8 billion headline equity value implies a demanding valuation for a logistics business still burning capital to expand its locker fleet across France, Spain, Italy, and the UK. It is a bet on what the network becomes, not what it earns today.
The UK segment is the honest stress test. Revenue from UK and Ireland grew 9.8% in Q2, yet adjusted EBITDA fell 39.9% year over year. InPost is absorbing the costs of transforming its UK and Ireland business after the Yodel consolidation. That drag is real and not yet resolved.
What FedEx Is Actually Buying
The strategic logic is cleaner than the near-term numbers. FedEx’s decision to invest in InPost will enable the company to improve network utilization by outsourcing lower-density B2C volumes to InPost, freeing capacity within FedEx’s system to prioritize higher-margin B2B volumes that are core to its growth strategy. That is the right trade if the commercial agreements deliver real volume at real economics.
FedEx and InPost will not integrate their operations and will remain independent competitors while entering arm’s-length commercial agreements after completion to connect FedEx’s global network with InPost’s last-mile delivery capabilities. InPost, in turn, will be able to draw on FedEx’s international transport network and customs-clearance capabilities. The network effect is credible. The execution risk is equally real.
The broader out-of-home market, lockers plus pickup and drop-off points, is widely expected to grow at a double-digit annual rate through 2030. FedEx is buying into that trend at scale rather than watching DHL, Amazon, and local operators claim the territory unchallenged.
How to Think About This as a Long-Term Shareholder
FedEx full-year fiscal 2026 revenue was $94.7 billion, up from $87.9 billion in fiscal 2025. The company has the financial weight to absorb this bet. The question is whether the InPost stake eventually shows up as a margin story or remains a strategic asset that never quite converts.
Long-term investors should track two numbers above all others: EBITDA per parcel in InPost’s Eurozone segment, which has been improving in mature markets, and volume growth driven by FedEx commercial referrals once those agreements go live. If FedEx’s 3 million business customers start routing European consumer deliveries through InPost lockers at meaningful scale, the acquisition earns its price. If the commercial relationship stays polite but thin, €8.9 billion will look like a lot of money spent to hold a minority stake in someone else’s infrastructure.
The parcel-locker model works. InPost has proven that across nearly a decade of expansion. The open question is whether FedEx can make the partnership add up faster than the debt compounds. That answer will take years, not headlines, to arrive.