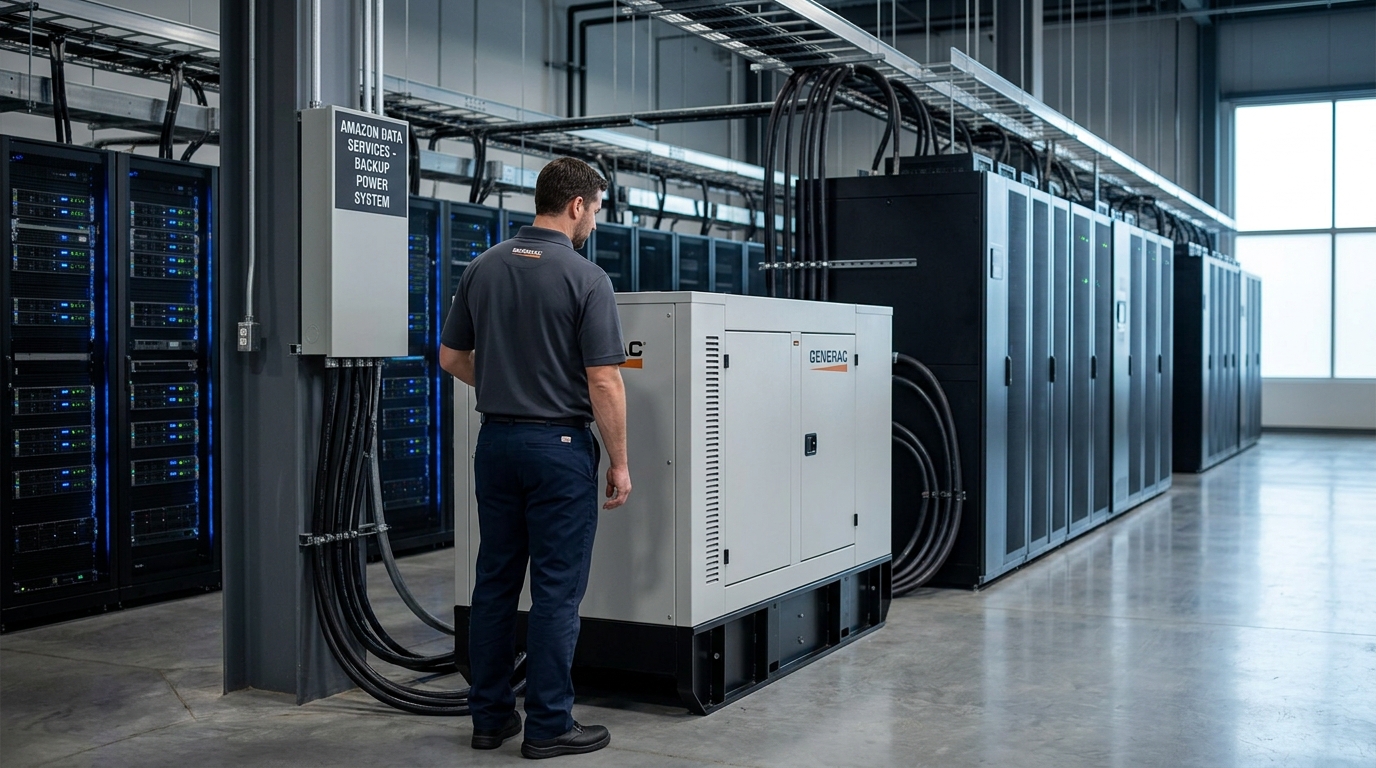
Generac has spent most of its public life at the mercy of hurricane season. A bad storm cycle sends the stock up. A quiet one drags it down. That era ended Tuesday, September 16, 2026, when an 8-K disclosed that Generac and Amazon entered into a long-term supply agreement for backup power generators for Amazon data centers, with purchases tied to payments of up to $8 billion, and that Generac issued Amazon.com NV Investment Holdings LLC a warrant covering up to 1,693,745 shares.
The market reacted immediately. Generac shares jumped as much as about 45% in after-hours trading on the news. By Thursday’s close, GNRC settled at $207.23, up about $32.12, or 18.34%. Today, September 18, the stock is around $207, with today’s intraday range not confirmed in this filing. The pullback from the overnight spike is normal. The business underneath it is not.
The Business
Generac makes power generation equipment, energy storage systems, and backup generators for residential, commercial, and industrial markets, with a growing focus on large-megawatt products sold into the global data center market. The data center segment was already accelerating before Amazon arrived. In Q2 2026, C&I revenues totaled $556.5 million, up about 29% year over year, and the company said its backlog for products serving the data center market had increased to approximately $1.6 billion.
That $1.6 billion backlog carried a footnote worth remembering: it did not include any committed volumes from the second hyperscale customer. The 8-K confirms Amazon is that second hyperscale agreement.
Why Wall Street Is Paying Attention
Initial deliveries are expected to total $2.4 billion in 2027 and 2028, with purchases potentially reaching up to $8 billion over the life of the deal. The warrant shares vest in multiple tranches contingent upon aggregate gross payments, net of certain offsets, received by Generac and its global affiliates from or on behalf of Amazon and its affiliates for backup power generators for Amazon data centers, up to a total of $8 billion. In other words, Amazon’s equity stake grows only as it pays Generac more money. That alignment is rare and significant.
Several firms highlighted the strategic scale of the contract. Cantor Fitzgerald reiterated its Overweight rating and a $333 price target, describing the agreement as Generac’s most significant data center announcement to date. Canaccord raised its target to $375 from $275 and kept a Buy rating.
The arrangement is the latest example of a tech giant striking a warrant-linked deal with a power supplier to keep up with AI-driven electricity demand. Bloom Energy has disclosed that it issued a warrant to Oracle dated April 9, 2026 in connection with their data center power partnership.
What’s Driving the Opportunity
The fundamental case rests on three layers that now stack cleanly. First, Generac was already winning data center business before this deal, with adjusted earnings of $2.91 per share in Q2 2026 and adjusted EBITDA of $291 million, or 24.8% of sales, compared with $188 million, or 17.7%, in the prior-year period. Second, the Amazon contract adds a multi-year revenue floor that analysts are still calibrating. Third, the average Wall Street price target of $305.50 implies substantial upside from current levels.
Capacity is expanding to meet demand. On its Q2 2026 earnings call, Generac said it was on track to begin production at its Sussex, Wisconsin large-megawatt facility by the end of Q3 2026, ahead of its initial target.
What Could Go Wrong
The warrant structure creates modest dilution. The warrant covers up to 1,693,745 shares, with 307,954 shares vested immediately and the remainder vesting over time based on Amazon’s payments. That is the ceiling, and it scales with revenue rather than arriving at once, but it is real dilution shareholders should price in.
The $8 billion figure is a ceiling, not a guaranteed order. The 8-K describes vesting as contingent on aggregate gross payments and also notes the purchases are subject to the structure and conditions in the warrant and transaction agreement. Execution risk on capacity expansion is genuine, and a slowdown in Amazon’s data center buildout would compress the timeline. The forward P/E figure in the draft is not confirmed here and can move quickly with price and estimate changes.
The Bottom Line
Generac is not the same company it was last week. It now holds a disclosed, structured commitment tied to Amazon’s data center generator spend, with initial deliveries expected to total $2.4 billion in 2027 and 2028 and payments tied to vesting up to $8 billion over the life of the agreement. The financial foundation was already improving before Amazon showed up. The warrant structure aligns incentives. Analyst targets cluster well above today’s price, and the sellside is broadly constructive.
The weather-dependent story is not the whole story anymore. The question now is how fast data center revenue ramps, and the answer to that sits inside Amazon’s own infrastructure spending plans. For investors willing to hold through delivery volatility, GNRC is today’s strongest single candidate.