September 15, 2026
Bonus Content: Centrus Energy’s $500M Offering Exposes a Valuation Gap
Washington Is Building. This Market Could Create a New Nasdaq Winner.
American strength has always come from building smarter, faster and better.
Small drones costing hundreds of dollars can now compete against tanks and military equipment worth millions.
That changes the economics of defense. The war in Ukraine has already proven just how powerful that advantage can be.
Washington sees the opportunity.
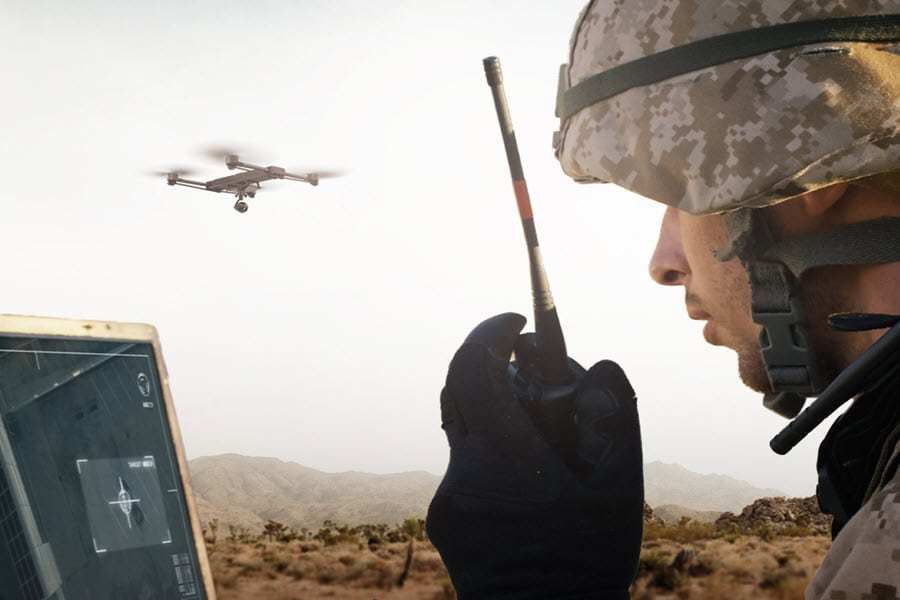
The Pentagon wants around 300,000 drones, while the government is prioritizing domestic manufacturing, secure supply chains and wider adoption of American made systems. America intends to lead this new market and build the technology here at home.
For investors, that push is happening inside a global drone industry projected to reach $182.4 billion by 2033.
One overlooked Nasdaq company has spent more than 25 years developing professional drone technology. It has patents, a broad product platform and systems already tested in real world missions.
Yet its shares are still trading under $5 for now.
If America leads the next era of flight, this quiet company may help power the charge.
Centrus Energy’s $500M Offering Exposes a Valuation Gap
Last Thursday, Centrus Energy priced a $500 million underwritten public offering of Class A common stock and warrants at $199.64 per share. By Friday’s close, the stock had shed roughly 17% across two sessions, extending a decline that has taken LEU from an October 2025 peak of $436 all the way to approximately $166. The drop is not because the business deteriorated. It is because the market is reassessing what kind of business Centrus actually is.
The operational record through mid-2026 is, by any fair reading, strong. Q2 revenue came in at $176.1 million, up 14% year over year. Adjusted EPS of $1.77 topped the Wall Street estimate that many outlets cited at about $0.97. Management raised full-year revenue guidance to $450 million to $500 million. The company has described a partially contingent backlog of about $3.7 billion in LEU and HALEU sales commitments, including approximately $3.0 billion in contingent LEU and HALEU sales commitments. And on July 1, 2026, Centrus signed the $900 million DOE task order to build commercial-scale HALEU production capacity at its Piketon, Ohio facility, with total contract value reaching $1.07 billion including options.
Yet the stock sits about 62% below its 52-week high while analysts maintain an average price target near $248. That gap reflects something specific: the market is questioning how much of the long-term thesis is already priced into near-term earnings, and whether the equity offering signals capital needs that could dilute returns before the big capacity additions come online.
The Piketon expansion, designed to add 12 metric tons of annual HALEU production capacity in its initial build-out, is not expected to bring the first new capacity online until 2029. In the interim, Centrus is operating its existing demonstration cascade, and it has been signing early supply agreements, including with X-energy, Radiant, and Oklo.
That said, the “only” framing needs precision. Centrus has long highlighted that its Piketon plant was the only U.S. facility licensed to enrich up to 20% U-235 when the NRC approved its license amendment in 2021, but the NRC now describes more than one U.S. licensee for HALEU production. Centrus remains a first mover with a rare domestic position, and it has disclosed that the NNSA has notified the company of its intent to sole-source certain uranium enrichment activities to Centrus.
The valuation friction is real, though. A P/E above 50x against flat GAAP net income growth, negative free cash flow, and a fresh wave of dilution from the offering creates a difficult calculus for value-conscious buyers. One analytical framework puts fair value near $190 per share, almost exactly where the stock traded before the offering landed. The offering itself priced at $199.64, suggesting Centrus and its underwriters believed fair value was closer to that level just days ago.
For long-term investors, the more relevant question is not where LEU trades this week. It is whether the company’s backlog, locked-in DOE relationships, and early lead in domestic HALEU enrichment will translate into the kind of earnings power in 2029 and beyond that justifies building a position at current levels. The capital raised in the offering is intended to support that buildout. Dilution now, if deployed well, becomes earnings later.
The core lesson here: when a company with a genuine structural advantage sells off hard after beating estimates and raising guidance, investors owe it to themselves to separate the business question from the valuation question. Centrus is not broken. The price simply got far ahead of where the cash flows are today, and the offering forced a reset. That reset may be the more interesting entry point.