November 3, 2026
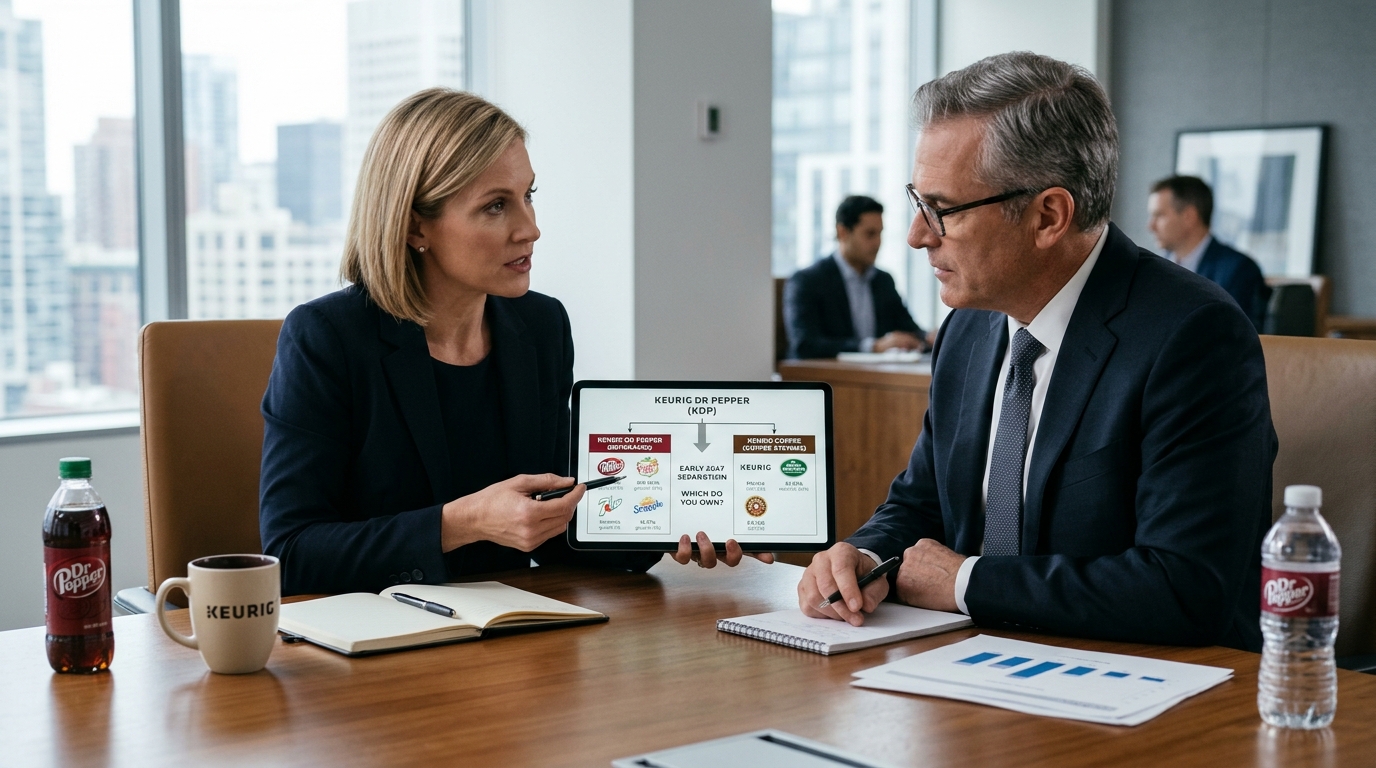
Bonus Content: Keurig Dr Pepper Split: Which Company Do You Want to Own?
Dear Reader,
You lock your doors. You shred your mail. You watch what you post online.
But on June 18th, five federal agencies, including the Federal Reserve, proposed a rule that reaches somewhere most people never think to protect…
Your money.
Private companies now issue their own digital dollars, used for payments and transfers online.
The new rule would require those companies to identify every customer the same way a bank does.
Your name, attached to every digital dollar you buy.
Most people missed it.
They were busy celebrating the July 11th ban on the Fed’s digital dollar, which does nothing to stop the private versions.
Now you might be thinking…
“I don’t use digital dollars. Why should I care?”
Because Bank of America, Wells Fargo, Citi and Capital One are among 21 financial institutions planning a joint one, targeting launch next year.
A digital dollar backed by Visa and Mastercard went live September 30th.
PayPal’s is already in Venmo.
Zelle has announced one too.
Sooner or later, the dollars in your accounts will likely move through these systems.
And any privacy-minded person should read this twice…
Right now, the rule only covers buying digital dollars from the company.
But the agencies are considering going further.
Tracking your name every time those dollars change hands.
Person to person. Payment to payment.
Public comments closed August 21st. Now the decision is up to them.
It’s being framed as crime prevention.
It always is… isn’t it?
What’s in your safe is yours. What’s in the bank is a promise.
Digital dollars work like the bank.
A company stands behind every one, and by law that company must be able to freeze them.
But some digital assets have no company or bank behind them at all. You hold them directly, like what’s in your safe.
That’s why I recorded a free presentation on our “Digital Dollar Immunity” System.
It shows how we hold a portion of our assets outside that system.
4,500+ members are already doing this.
If you have $50k+ saved for retirement and want to protect your family from whatever comes next, watch it now:
Click Here To Reveal The “Digital Dollar Immunity” System →
To your wealth,
Tan Gera, CFA®
Decentralized Masters
P.S. The public comment window closed August 21st. The final rule is still coming.
Keurig Dr Pepper Split: Which Company Do You Want to Own?
Keurig Dr Pepper is reporting its third-quarter results this morning, and the numbers will matter less than the question shareholders have roughly three months to think through: when a company splits in two, which half do you keep?
This is KDP’s first earnings update since naming new leadership for the planned separation into two independent companies early next year. The mechanics are largely set. As part of its roughly $18 billion acquisition of JDE Peet’s, KDP is planning to split into two U.S.-listed companies, Global Coffee Co. and Beverage Co., with the separation expected in early 2027.
The debt allocation is where this gets complicated for investors. KDP’s updated financing plan assigned much of the acquisition burden to Global Coffee Co., with that entity expected to raise about $9 billion of long-term debt and assume roughly $5 billion of existing JDE Peet’s bonds. Meanwhile, KDP is targeting a pro forma management leverage ratio of 4.1x at year-end across the combined company before the split occurs. That is a significant load to carry into a rate environment that has not made debt cheap.
The future Global Coffee Co. will combine KDP’s coffee operation with JDE Peet’s, creating a company expected to generate approximately $16 billion in annual revenue after separation. Scale is real. But for Global Coffee Co., leverage, leadership and coffee input costs will matter most. The leadership situation alone has been unsettled: Rafael Oliveira, who had been selected to lead Global Coffee Co. following the JDE Peet’s acquisition, departed after accepting the CEO position at Heineken, and KDP launched a search for his successor. Russ Torres, previously president and chief operating officer at Kimberly-Clark, joins KDP today as incoming CEO of the coffee unit.
Beverage Co. is the cleaner story. At 15 times EBITDA, Bank of America estimates Beverage Co. would be worth approximately $31 per current KDP share, meaning the majority of BofA’s $38 valuation for Keurig Dr Pepper comes from the beverage side. KDP’s third-quarter performance is likely to have benefited from sustained momentum in U.S. Refreshment Beverages, with demand for Dr Pepper Zero Sugar and Canada Dry, along with continued growth in energy drinks, supporting sales. Tim Cofer, current CEO, will lead Beverage Co. after the separation, giving that business continuity at the top.
The market may ultimately value the two companies on very different metrics: branded-beverage growth and margins on one side, global coffee scale, synergies and deleveraging on the other. That divergence is already visible in analyst estimates. Bank of America estimates the coffee company could command roughly six to eight times EBITDA, a meaningful discount to where consumer staples businesses typically trade. Coffee commodity costs and the weight of debt are the reasons.
Management has indicated that separation preparations remain on track, with significant progress in integration, organizational restructuring and separation readiness, and the proposed split could allow each company to sharpen its strategic priorities and pursue opportunities aligned with its respective markets. Management expects both businesses to deleverage quickly following the separation, potentially creating greater flexibility for future capital deployment.
Today’s Q3 report is the last full-quarter look at KDP as a single entity. Analysts expect earnings of roughly $0.62 per share on revenue of $7.33 billion. Whether those numbers land above or below consensus matters less for long-term holders than the debt path between now and separation day.
The enduring lesson here applies beyond KDP: when a company divides itself, the press release will describe two growth businesses. The balance sheet will tell you which one is actually starting from a position of strength. Read the debt split before you decide what to hold.