Why This Stock Now
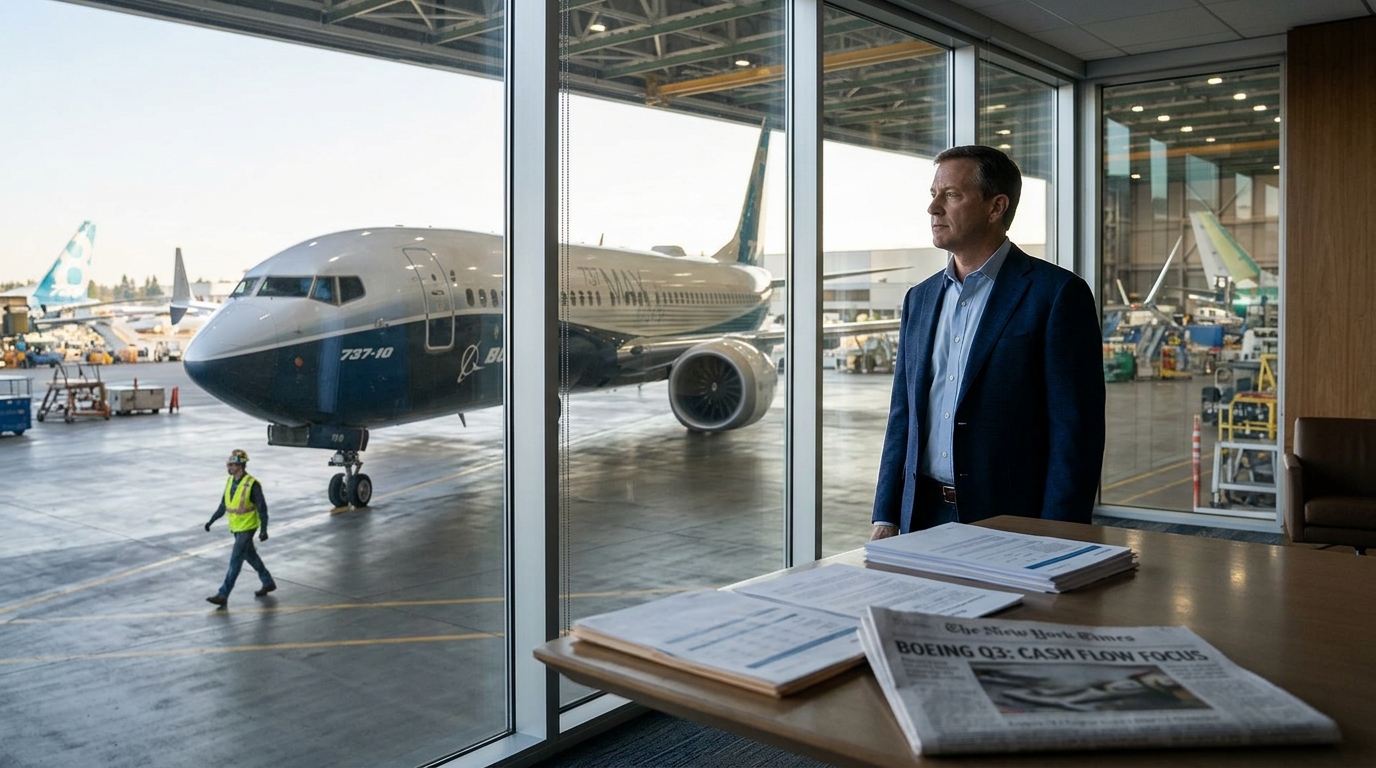
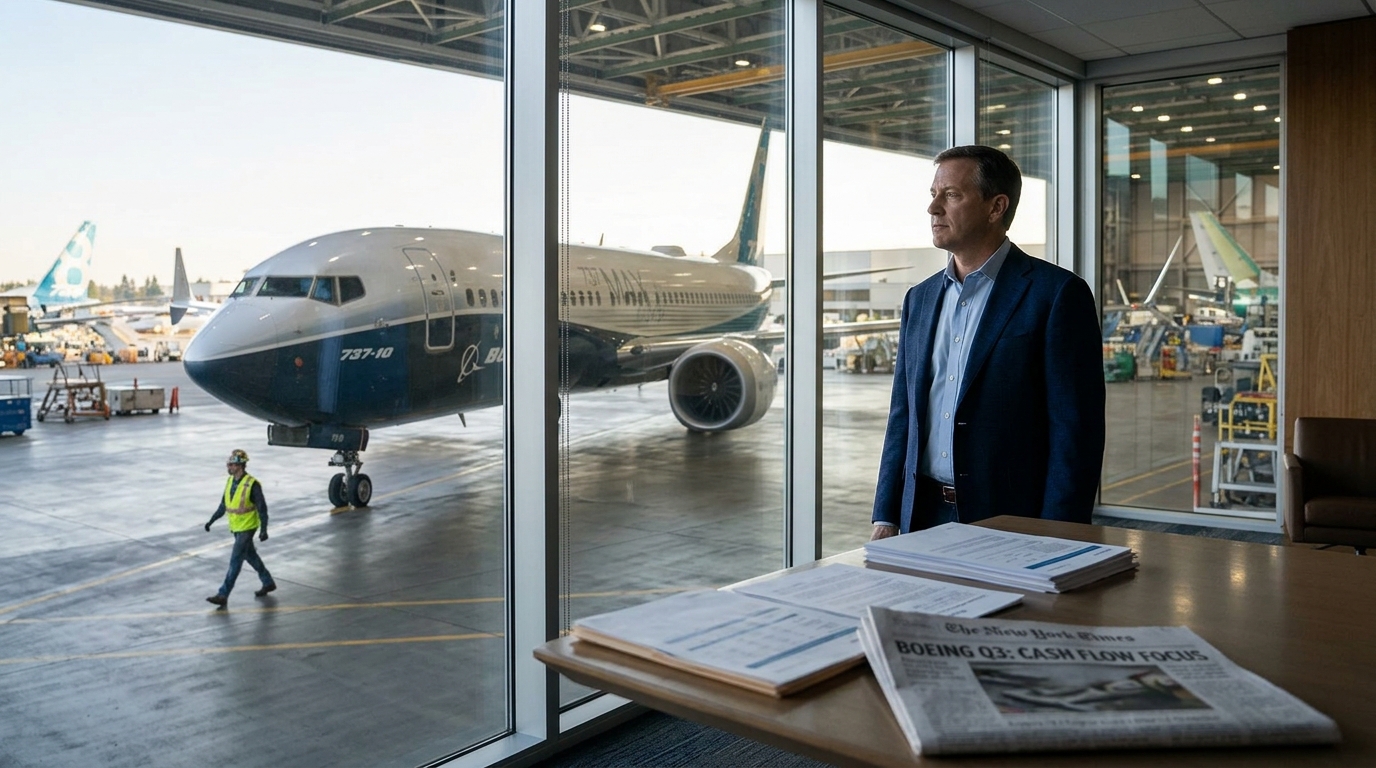
Boeing (BA) reports third-quarter results this morning, and the timing is complicated. The FAA certified the 737-10 on October 20, the Navy selected Boeing for F/A-XX, and a new labor contract removed strike risk. Those are genuinely meaningful wins. Shares are still down nearly 15% since the last report. This quarter tests whether regulatory wins can turn into cash.
The Business
Boeing makes commercial jets, military aircraft, and space systems. Its commercial airplane division is the one that almost destroyed the company between 2019 and 2025, and it is the one that Wall Street is watching most carefully now. The company enters this report with a record backlog of $715 billion, including more than 6,200 commercial airplanes. That backlog is not the question. Converting it to cash is.
Revenue is projected to increase by about 4.7% to roughly $24.37 billion, driven in part by 57 commercial aircraft deliveries in September, the highest monthly output for 2026, contributing to 475 deliveries over the first nine months, an 8% increase from the prior year.
Why Wall Street Is Paying Attention
The year-ago comparison is almost irrelevant. Q3 2025 was heavily impacted by a $4.9 billion 777X charge and negative free cash flow. Q3 2026 consensus expects a smaller loss and higher revenue year over year.
But the EPS line is not where analysts are focused. For Boeing, a good morning means positive free cash flow despite the DOJ payment. Free cash flow is the number that matters most. Management has said it expects Q3 free cash flow to be positive in the low hundreds of millions despite a $700 million DOJ payment, and it has reiterated a full-year outlook of $1 billion to $3 billion. If that holds, the recovery is on track. If it doesn’t, the stock goes back to scrutinizing every production line.
The DOJ payment is not the only variable that shifted heading into this report. The 737 MAX 10 certification changes the cash flow calculus by unlocking deliveries of Boeing’s highest-capacity single-aisle variant.
What’s Driving the Opportunity
The 737 ramp is the core driver. Boeing is executing on production rate increases with the 737 MAX moving from 42 per month toward 47 per month, the North Line in Everett started in July, and management has discussed progress toward 52 per month in 2027.
The gap between a massive order book and actual cash generation is not unique to Boeing. General Dynamics faces the same execution test on a $136.5 billion backlog, where production capacity rather than demand is the binding constraint.
Boeing’s current price-to-sales ratio stands at about 1.57, notably below its historical median (roughly 1.8x). If fiscal year 2027 brings the first genuinely profitable year since 2018, the multiple re-rating alone could be significant. Analysts currently forecast adjusted EPS around $3.8 in fiscal 2027.
What Could Go Wrong
Investors are still watching persistent production constraints across programs, and whether Boeing can improve delivery efficiency and cash flow. There is also the history: the Q3 EPS consensus has slipped to roughly a $0.20 loss over the past 90 days, with more downward than upward revisions recently. That pattern suggests analysts keep finding reasons to be cautious.
The stock has also responded poorly to good news. Boeing locked down the FAA certification it spent years chasing, signed a big Navy fighter deal, and reduced near-term strike risk, yet shares kept falling and analyst estimates kept dropping. A stock that ignores positive catalysts is a stock the market doesn’t fully trust yet.
The Bottom Line
The case for BA is not complicated. A company with $715 billion in backlog, improving monthly delivery rates, and a narrowing loss should eventually be worth substantially more. The question has always been how long it takes to get there, and whether the cash flow trajectory is real. This morning’s report answers that directly. Positive free cash flow after absorbing a $700 million payment would be hard evidence the turnaround is gaining traction. That is not a speculative argument. It is a measurable one, and it arrives before the open.