October 6, 2026
Bonus Content: S&P 500 Earnings Are About to Test the Rally Beyond Tech
Below is an important message from one of our highly valued sponsors. Please read it carefully as they have some special information to share with you.
Dear reader,
A few years ago, every expert swore Elon Musk would never build a car that could drive itself.
A top federal safety adviser said, “you are never getting real self-driving.”
Ford called the whole effort “vaporware.”
But they were dead wrong. Today, Tesla’s robotaxis pick up paying passengers, with no one in the driver’s seat, in cities across America.
I have ridden in one myself.
Here’s why that matters to you, today:
Elon cracked self-driving by putting eyes on the car and letting it watch and learn from countless hours of footage. And he is about to unleash the exact same playbook on his next breakthrough.
He calls it his “infinite money glitch,” and he predicts it will be the biggest product launch in history. I expect it will enter production as soon as October 21.
I have spent almost forty years investing in technology, and this is easily the biggest breakthrough I have covered yet.
I put the whole story into a short presentation. Watch it before October 21.
â¶️ Watch the presentation here.
Regards,
James Altucher
S&P 500 Earnings Are About to Test the Rally Beyond Tech
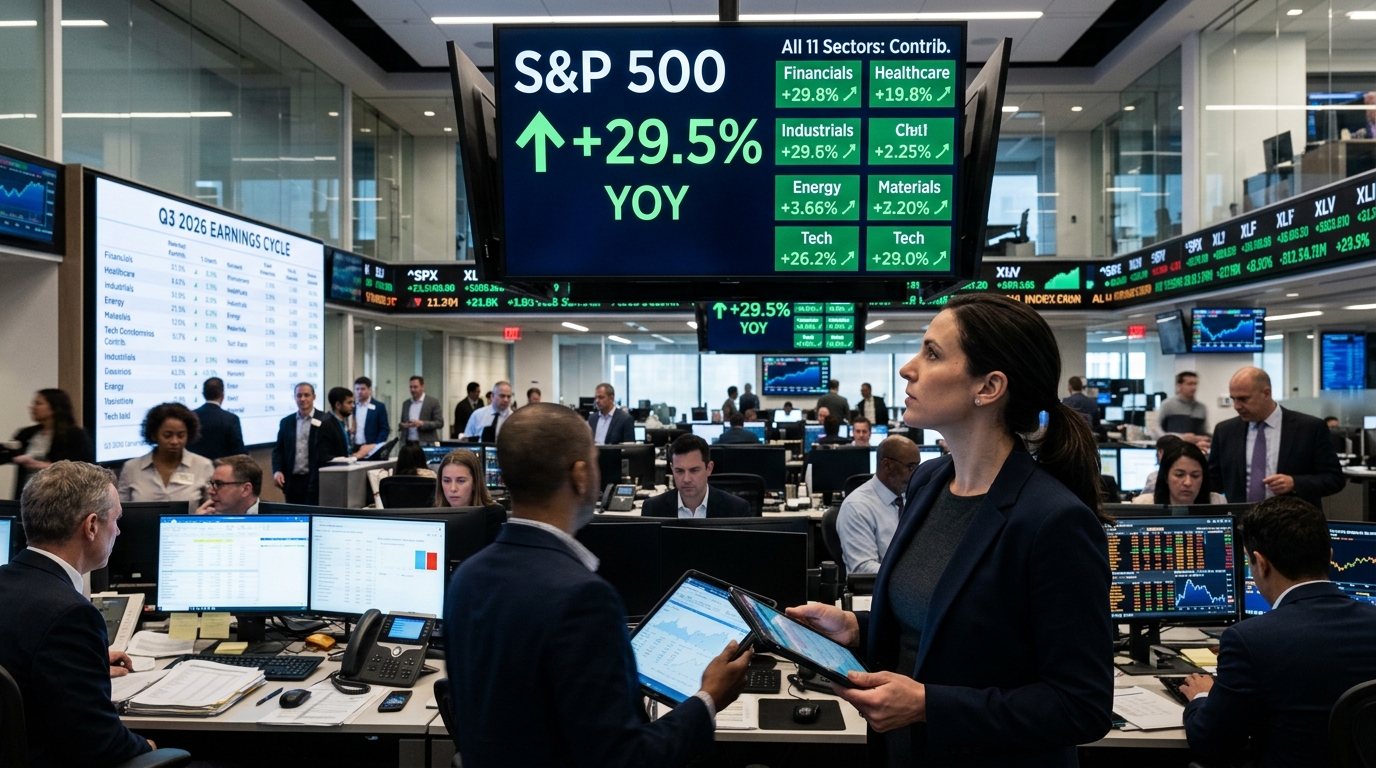
The number Wall Street is carrying into this week is 29.5%. That is the estimated year-over-year earnings growth rate for the S&P 500 in Q3 2026, according to FactSet’s October 2 Earnings Insight. If that rate holds, it will mark the third consecutive quarter of earnings growth above 25% for the index. Three straight quarters above that threshold. That is not a fluke; it is a cycle.
What makes this quarter genuinely different from the usual run-up to earnings season is how analysts got here. Estimates do not normally rise heading into reporting season. Companies and analysts routinely guide lower to manufacture beats. Q3 2026 broke that pattern: the bottom-up EPS estimate rose 1.4% between June 30 and September 30. On top of that, 62% of the companies that issued guidance issued positive guidance, well above recent averages. In plain terms, companies and analysts both raised the bar.
The Bigger Trend
The bar being raised does not guarantee it gets cleared, but it does say something important about corporate confidence. Revenue expectations moved in the same direction: as of October 2, the S&P 500 is expected to report year-over-year revenue growth of 12.3%, compared to expectations of 10.9% on June 30.
Here is the part that matters most for investors who hold anything outside of large-cap technology: all eleven sectors are projected to report year-over-year earnings growth, with five of those sectors predicted to report double-digit growth, led by Energy, Information Technology, Communication Services, and Materials. All eleven growing at once has not happened since 2021. Historically, upward estimate revisions were tightly concentrated in Technology. For Q3 2026, revisions have broadened, including industries such as Transportation, Finance, Aerospace, Industrials, Utilities, and Construction.
That breadth is where the real opportunity lives for long-term investors. The AI buildout is large enough that its spending has become other industries’ revenue.
The Investment Case
The earnings calendar opening this week provides a useful lens. Delta Air Lines reports October 9. Delta’s result will signal how much of the consumer spending resilience is holding in travel. JPMorgan follows on October 13, where consensus expects Q3 revenue of about $50.8 billion and EPS of $5.86, with management having raised full-year net interest income guidance to approximately $96.5 billion excluding Markets after Q2. For investors in financial stocks, JPMorgan’s report is effectively the first data point on whether higher yields are translating into sustained net interest income growth, and whether credit quality has held.
Financials and Industrials reporting strong, broad numbers this season would shift the conversation meaningfully. Broader market participation beyond a narrow set of AI-linked leaders could make earnings strength look more durable going into the fourth quarter.
Building Wealth Around This Idea
A 29.5% headline growth rate deserves a closer look before it informs any allocation decision. One large-bank strategy note has argued that a majority of Q3 earnings growth may come from a small number of companies, which underscores the concentration risk. The concentration risk is real. But if the non-tech sectors deliver on their elevated estimates, that concentration begins to loosen, and portfolios with exposure to financials, industrials, and energy benefit without requiring a single AI megacap to do anything new.
Position size matters here as much as stock selection. This is not a moment to overweight one theme on the strength of one quarter’s estimates. It is a moment to make sure the portfolio reflects the breadth that the earnings data is beginning to confirm. Valuation is also part of the backdrop. Recent FactSet data has shown the S&P 500’s forward 12-month P/E around the high teens, below its five-year average and near its ten-year average. That valuation is not stretched in the way it was earlier this cycle, which means earnings, not multiple expansion, are doing the work.
Risks to Monitor
The bar at 29.5% is the highest of this cycle. Beats that fail to move stocks are the key warning sign. If strong results produce weak price reactions, valuations, not earnings, are controlling the market. Watch JPMorgan’s credit quality commentary closely; card delinquencies and net charge-off rates have been a quiet pressure point. And watch Delta for any signal that premium travel demand, the most durable part of the consumer, is softening.
Daily Wealth Takeaway
The most important insight from this earnings season is not whether the S&P 500 hits 29.5% growth. It is whether that growth is coming from more than ten companies. Durable wealth is built in broad markets, not concentrated ones. This week begins the answer.