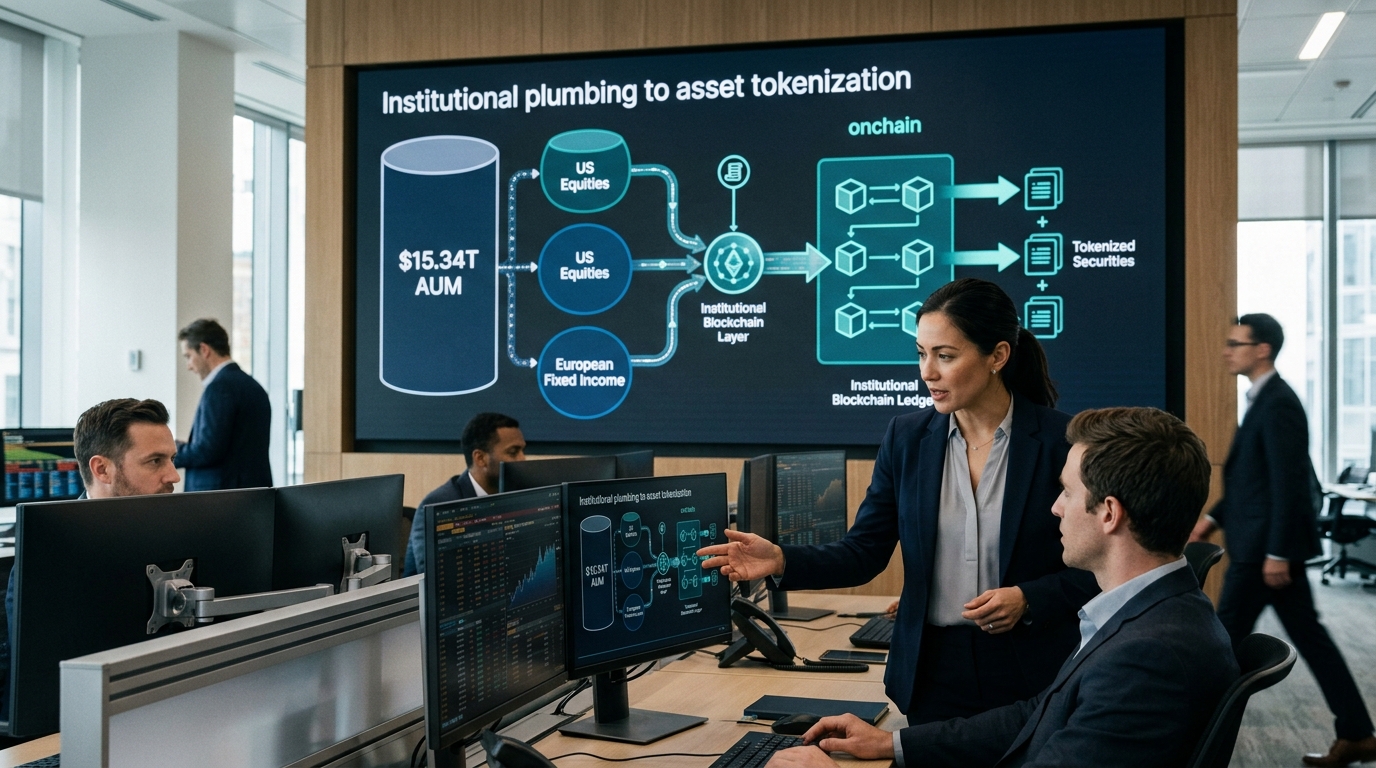
The financial world tends to conflate tokenization with cryptocurrency speculation. BlackRock is doing something more deliberate, and the flow numbers are large enough to pay attention to now.
BlackRock’s AUM reached $15.34 trillion at June 30, 2026, up from $12.53 trillion at the same point a year earlier, driven by market appreciation, net inflows, and assets added from the HPS and ElmTree acquisitions. That headline figure obscures where the real strategic bet is being placed. Inside those numbers, private markets net inflows in Q2 2026 were about $15 billion, led by private credit and infrastructure. That is not a passive byproduct of markets rising. It reflects deliberate institutional reallocation toward higher-fee, illiquid strategies, and BlackRock is a major beneficiary of that shift.
The tokenization layer is where the next chapter of that story gets written. BUIDL, the BlackRock USD Institutional Digital Liquidity Fund launched in March 2024, has grown to roughly $0.9 billion visible onchain across six deployments as of September 24, 2026, making it one of the larger tokenized U.S. Treasury-style products in the market. That trajectory from zero to nearly $1 billion in a little over two years is not slow-money institutional caution. It is adoption.
The firm did not stop there. On May 8, 2026, BlackRock filed with the SEC for a new tokenized fund. Then in August, BlackRock moved into Europe. Building on its U.S. tokenized cash expansion, the firm unveiled 12 new tokenized share classes based on six funds across 15 European markets, with the underlying Institutional Cash Series range representing a combined $311 billion in assets under management as of June 30, 2026. The Institutional Cash Series funds were tokenized in collaboration with JPMorgan using the bank’s Kinexys platform.
The strategic logic is straightforward: money market funds are a $10-trillion-plus global market, most of it still moving through legacy settlement rails. The tokenized funds are designed for corporate treasurers who already use money market funds to manage operating and reserve cash, as well as asset managers and investment consultants across traditional and digital markets. Tokenizing those instruments does not change the underlying credit risk. It changes the speed and programmability of the cash itself, which is what institutions running stablecoin reserves and digital collateral pools actually need.
BlackRock has disclosed that it manages the Circle Reserve Fund, the government money market fund used for a substantial share of USDC reserves. That position makes BlackRock a reserve manager of record for a meaningful share of dollar-denominated digital liquidity. BlackRock has said it has about $110 billion in AUM connected to digital assets, and management has discussed an ambition to grow this into a $500 million annual revenue business by 2030.
For investors, the question is less about whether tokenization works and more about who captures the fee stream. BlackRock’s operating margin reached 45.9% in Q2 2026, and the company has said it aims for 30% or more of revenue from private markets and technology by 2030, with continued margin expansion expected through higher fee rates and technology deployment. Tokenized fund structures, because they reduce settlement friction and attract stickier institutional capital, support both sides of that equation.
The broader tokenized real-world asset sector has surpassed $30 billion in onchain value, roughly tripling over the prior year based on RWA.xyz-tracked data. BlackRock controls a meaningful share of that market and is positioned to grow it through relationships few crypto-native issuers can replicate: global regulatory standing, $15 trillion in existing client relationships, and custodial infrastructure through BNY Mellon.
The risk to watch is regulatory. BlackRock is navigating a complex regulatory environment, particularly in digital assets and tokenization, which could pose challenges to its strategic initiatives. A shift in SEC posture or a tougher enforcement stance in Europe could slow product rollouts. Fee compression from competitors entering the tokenized money market space is a longer-term concern.
The wealth takeaway: tokenization is not a product category anymore. For BlackRock, it is becoming infrastructure revenue, the kind that compounds quietly inside the fee line while the market focuses on ETF flows. Investors who understand that distinction own the stock differently than those who still see BLK as just an index fund company.