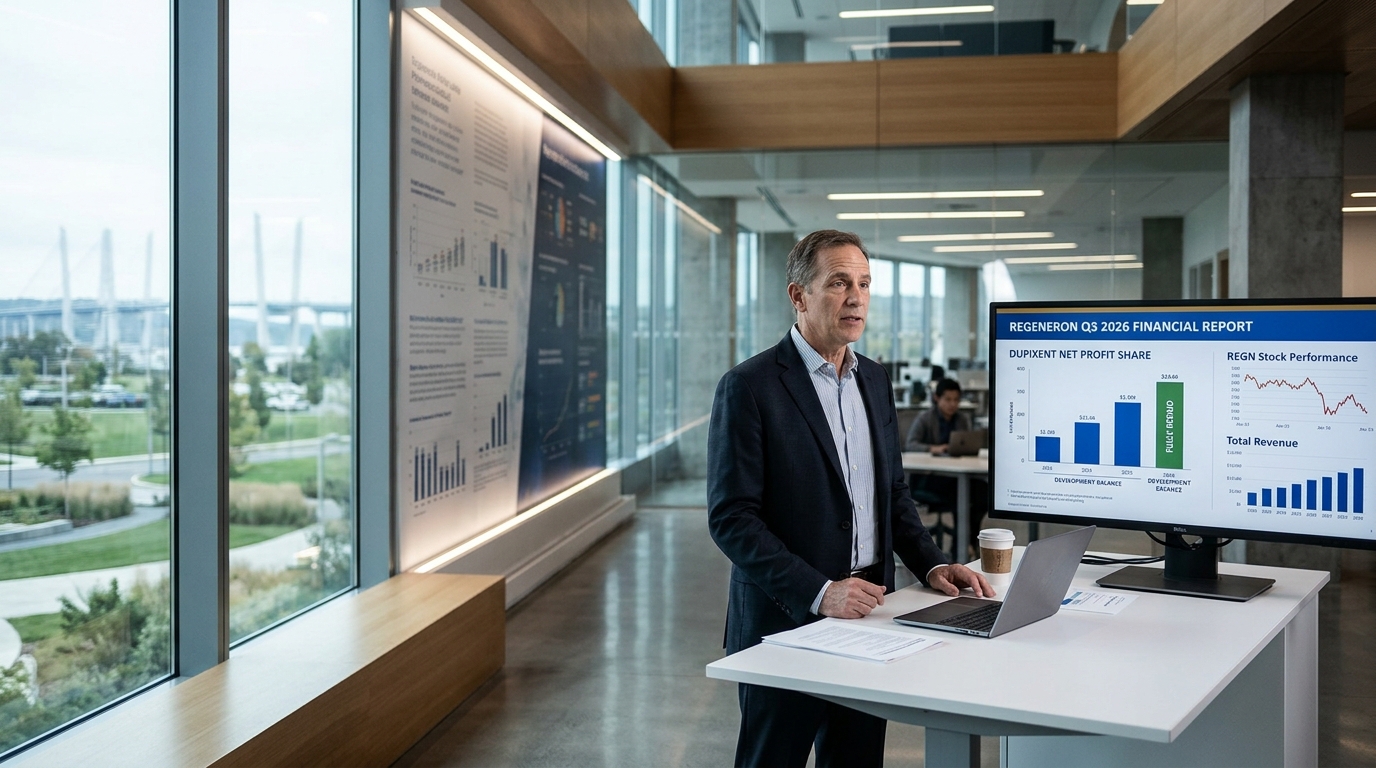
Regeneron Pharmaceuticals reported third-quarter 2026 results before the opening bell this morning, and the number Wall Street watches first is not earnings per share. It is how much Dupixent is actually contributing to the bottom line now that the accounting fog has lifted.
The Structural Change Most Investors Missed
The Sanofi Development Balance was fully repaid as of June 30, 2026 and will no longer reduce Sanofi collaboration revenue beginning in the third quarter of 2026. That sentence, disclosed in the company’s Q2 materials and subsequent 10-Q, is the single biggest change to Regeneron’s reported financials in years. REGN will book its full Dupixent profit share for the first time in Q3, after the development balance had been reducing Sanofi collaboration revenue in prior periods. For the first time, investors can see what Dupixent is genuinely worth to the income statement without a large repayment-related drag obscuring the view.
The consensus heading into this morning’s report called for roughly $16.02 to $16.19 in non-GAAP EPS on revenue of approximately $4.54 to $4.56 billion. If the company hits those targets, it would mark a sequential improvement from the prior quarter’s results. That kind of earnings-to-revenue spread would signal real operating leverage rather than just volume.
The Eylea Question Is Real but Answerable
Every Regeneron quarter for the past two years has carried a version of the same anxiety: can Dupixent outrun legacy Eylea’s decline? The Q2 data settled that debate more decisively than many expected. Dupixent global net sales reached $6.0 billion, up 38% year-over-year. EYLEA HD U.S. net sales hit $596 million, up 52%. Legacy EYLEA U.S. net sales declined 45% year-over-year due to ongoing conversion to EYLEA HD and competitive dynamics.
The math is already running in Regeneron’s favor. EYLEA HD is not just replacing legacy Eylea; it is growing the franchise’s total economics while carrying a better margin profile. If Eylea HD continues outpacing the decline in legacy Eylea, Regeneron enters 2027 with its growth engine running at full strength. Q3 will show whether that trend extended through September or hit a seasonal speed bump.
A Depressed Stock with Accumulation Logic
REGN sits near $819 this morning, off about 31% from its all-time closing high of $1,191.92 reached on August 27, 2024. The company has a market cap of about $87 billion and a 52-week range that has been cited around $591.52 to $859.34. Against that backdrop, valuation is the part of this story that should hold a patient investor’s attention longest. With a forward price-to-earnings ratio and projected growth that many screens still show as unusually low relative to large-cap biotech, Regeneron appears positioned for the next phase of growth.
Analysts have been moving targets higher into today’s report. Canaccord Genuity raised its price target from $875 to $922 and maintained a buy rating on October 28. UBS upgraded REGN to buy from neutral in mid-October and raised its price target to $978 from $660. These are not small increments. They reflect genuine reassessment of what Dupixent’s clean profit share looks like compounded forward.
Beyond the two core drugs, the pipeline adds optionality that the stock’s valuation does not fully credit. The FDA has assigned the NDA for cemdisiran a target action date in November 2026 for generalized myasthenia gravis, making the upcoming decision effectively a near-term binary event. Regeneron also announced a contract extension to supply its Ebola therapy, Inmazeb, to the U.S. government through 2031 for approximately $270 million in expected payments, adding durable government revenue that has nothing to do with either franchise debate.
How to Think About Owning This
Regeneron is not a turnaround. Revenue has grown year-over-year in each of the first two quarters of 2026. The stock is depressed because 2024 investors paid too much at around $1,192, not because the business deteriorated. The Q3 report answers a specific question: does the clean Dupixent profit share deliver the step-up in collaboration revenue that analysts modeled? If it does, REGN trading at a low-teens forward multiple starts to look like a pricing error that the market corrects over the next four to eight quarters.
The repricing logic extends beyond Regeneron alone. Institutional capital has been rotating into biotech names where pipeline optionality is underpriced relative to risk-adjusted net present value.
Position sizing discipline matters here. Healthcare stocks with pending FDA decisions, a dominant product still in mid-cycle growth, and depressed valuations fit a core-holding allocation rather than a speculative one. The time horizon should be at least 18 months. Biosimilar pressure on legacy Eylea will not reverse, but REGN’s future growth is anchored by Dupixent’s expanding indications, a robust late-stage pipeline, and improving Libtayo performance, offsetting Eylea’s decline.
The Wealth Builder Takeaway
The most enduring wealth-building insight from a quarter like this is simple: a great business trading far below its recent high is not the same as a broken business. Regeneron’s revenues grew 17% year-over-year in Q2 2026, and by the end of June it held roughly $15 billion across cash, cash equivalents, and marketable securities. The market priced it near $1,192 when the outlook was murkier; it prices it near $819 today with more clarity. That gap is either an opportunity or a warning. Today’s revenue tells you which.