October 29, 2026
Bonus Content: Nvidia Needs $600 Billion in Revenue to Hit $10T. The Math Is Starting to Work.
Dear Reader,
I’m convinced that AI’s next phase will blindside millions of American investors.
And it has NOTHING to do with the recent “tech wreck.”
But I believe if you have any money in the stock market or a 401(k), it’s imperative you make one straightforward move immediately…
A move that I’ll explain, for free, right here.
This isn’t my first bold AI prediction.
- I recommended Nvidia all the way back in 2015, before it went on to surge over 21,000%.
And years before AI became a household term, I developed a 20-factor computerized stock-rating system to identify tomorrow’s winners on Wall Street… TODAY. - That system recently identified AI winners such as Sandisk, before it rose 300% in just a few months.
- It flashed bullish on data-storage company Seagate, before it rocketed 393% in months.
- And Micron Technology, before an 827% gain in just a year.
But there’s a reason most folks didn’t catch these ahead of time.
Each of these stocks took off thanks to a powerful ripple effect spreading through the AI economy.
And my research suggests that ripple is now moving somewhere new.
I’m sharing all the evidence to prove why AI’s next phase could generate the biggest and fastest financial windfalls I’ve seen in my 60-year career…
And the straightforward move I believe you should make now, before the next wave hits.
Get the full story and see the name of my No. 1 recommendation here.
Be well,
Marc Chaikin
Founder, Chaikin Analytics
Nvidia Needs $600 Billion in Revenue to Hit $10T. The Math Is Starting to Work.
The $10 trillion conversation around Nvidia used to feel like science fiction. It no longer does.
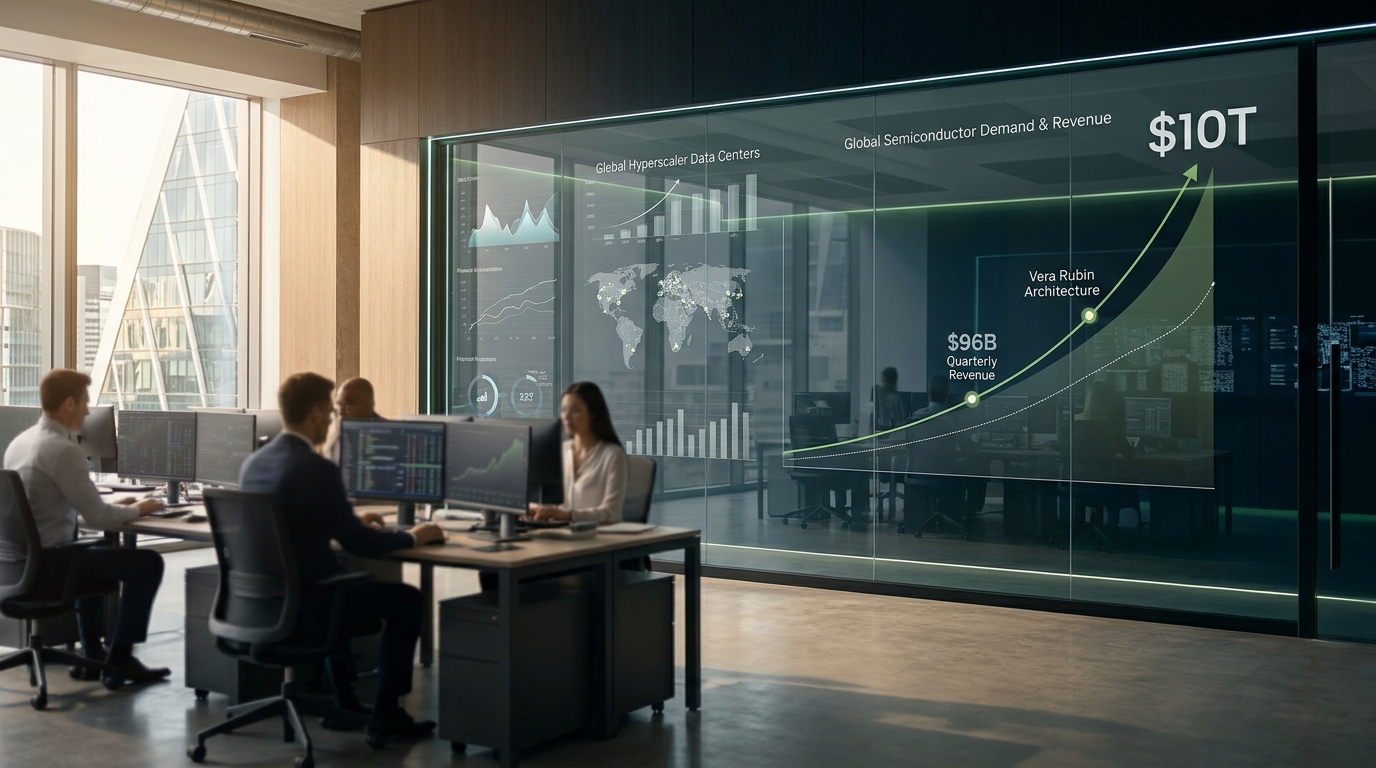
Nvidia is currently about a $5.2 trillion company. Getting to $10 trillion requires roughly a 94% gain from here. That sounds steep until you look at where the revenue is going. Nvidia’s most recent quarterly result came in at $96.2 billion, up 106% from a year ago, with data center revenue of $89.0 billion rising 117% year over year. A company growing this fast has a different relationship with large round numbers than a mature industrial stock does.
The clearest path to a $10 trillion valuation runs through earnings, not sentiment. At a price-to-earnings ratio of 30, Nvidia would need to generate about $333 billion in net income to justify a $10 trillion market cap. That figure still sounds distant, but Nvidia’s gross margins give it an unusually short runway to get there. Gross margins for the most recent quarter held at 75%. Apply that margin profile to a revenue base that analysts expect to keep compounding and the net income target becomes a 2028 or early 2029 story, not a 2035 one.
Where the Revenue Comes From
The angle most investors are underweighting is the per-gigawatt revenue expansion from Nvidia’s newest platform. Nvidia’s CFO said its revenue opportunity per gigawatt has grown from roughly $18 billion with Hopper to $25 billion with Blackwell and $40 billion with Vera Rubin. That is not a chip upgrade. It is a reset of the entire infrastructure stack, and it means Nvidia grows revenue even if data centers add no new power capacity at all.
Vera Rubin is already shipping. Production shipments began in early August 2026, and management expects Vera Rubin to comprise about 20% of data center revenue in fiscal Q3 2027. The Q3 revenue guide itself tells the story: management guided Q3 revenue to $108 billion, plus or minus 2%.
On the demand side, the numbers coming from Nvidia’s largest customers are not slowing. Morgan Stanley estimates hyperscalers and AI cloud providers will spend $1.58 trillion in 2027, up roughly 60% from about $980 billion this year, with about $1 trillion of that 2027 spending landing as S&P 500 revenue and nearly $700 billion of it going to Nvidia. Sovereign AI is adding another layer. Nvidia has said its sovereign AI business more than tripled to over $30 billion in fiscal 2026.
Hyperscaler capex at that scale does not flow to Nvidia alone. Broadcom’s custom silicon division captures a growing share of the same hyperscaler budgets funding Nvidia’s order book.
What Could Derail It
The risks are real and worth naming precisely. Supply is the binding constraint right now. Management has described the outlook as supply constrained, with the supply chain running at full capacity. A stumble in the Vera Rubin ramp, or a shift in hyperscaler return-on-investment calculus, could pressure both revenue and the multiple simultaneously.
Gross margin is expected to ease from 75% in fiscal Q2 to 71%-72% in fiscal Q4 before settling at 72%-73% in fiscal 2028. That compression is modest, but investors should track it. A $10 trillion valuation demands both revenue scale and margin durability, not one or the other.
Margin durability also depends on whether data centers can keep expanding capacity. Power grid constraints are emerging as the binding limit on how fast AI infrastructure spending can actually grow.
The Wealth Builder Takeaway
Nvidia is not a lottery ticket on $10 trillion. It is a business generating nearly $400 billion in annualized revenue, growing at triple digits, with a platform transition underway that expands revenue per unit of capacity by 60%. The milestone is a byproduct, not the goal. Long-term investors who focus on the earnings trajectory rather than the market cap headline are reading this correctly.