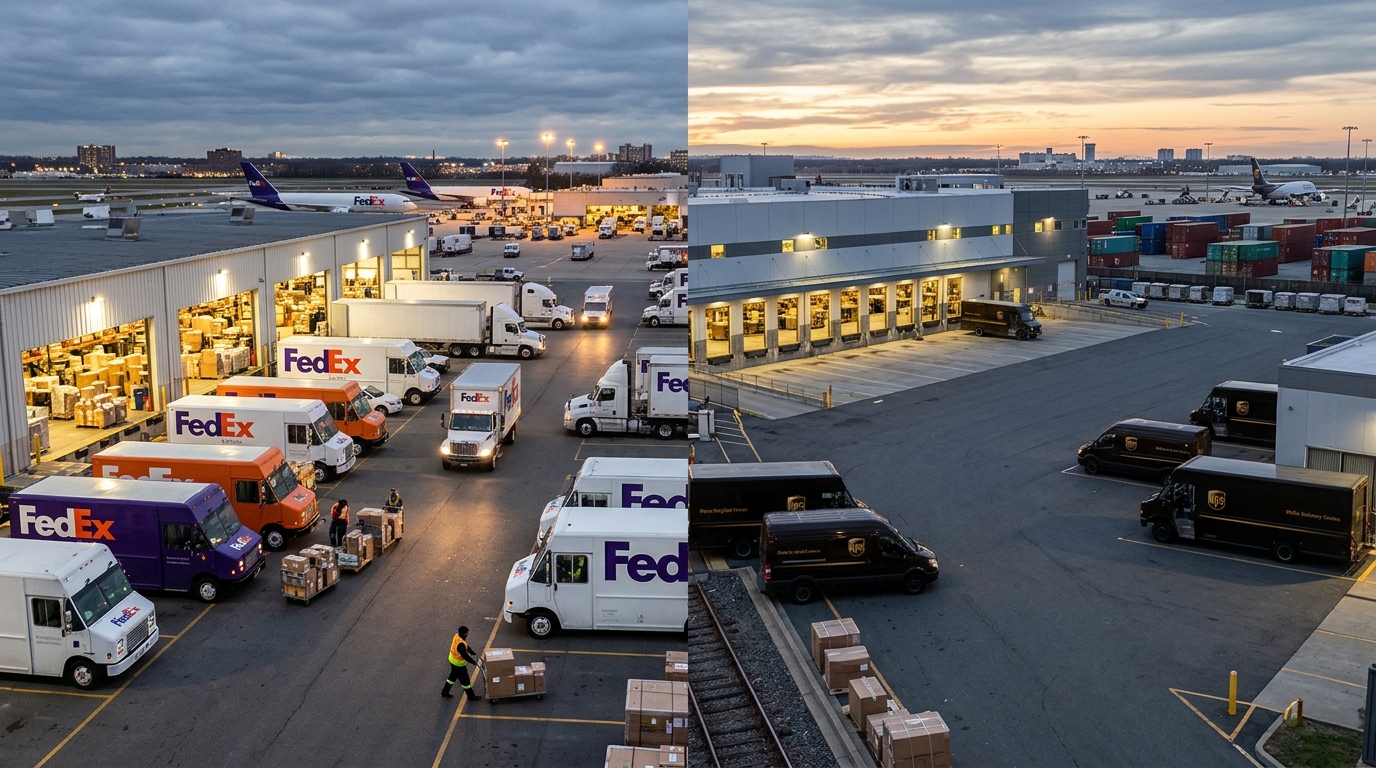
The most revealing thing about FedEx’s October 28 earnings was not the headline numbers. It was the direction management chose to run while diesel costs $6.352 a gallon nationwide and the holiday clock is ticking. Revenue was up 12% year over year and adjusted diluted EPS came in at $3.74, representing 28% growth from $2.93 in the prior year period. More pointedly, FedEx chose that moment to raise the full-year outlook.
Calendar 2026 adjusted EPS guidance now stands at $18.00 to $18.60, raised and tightened from the previous range of $16.90 to $18.10. The midpoint implies about 23% adjusted earnings per share growth year over year for the full year. That is not the language of a company bracing for a soft Q4.
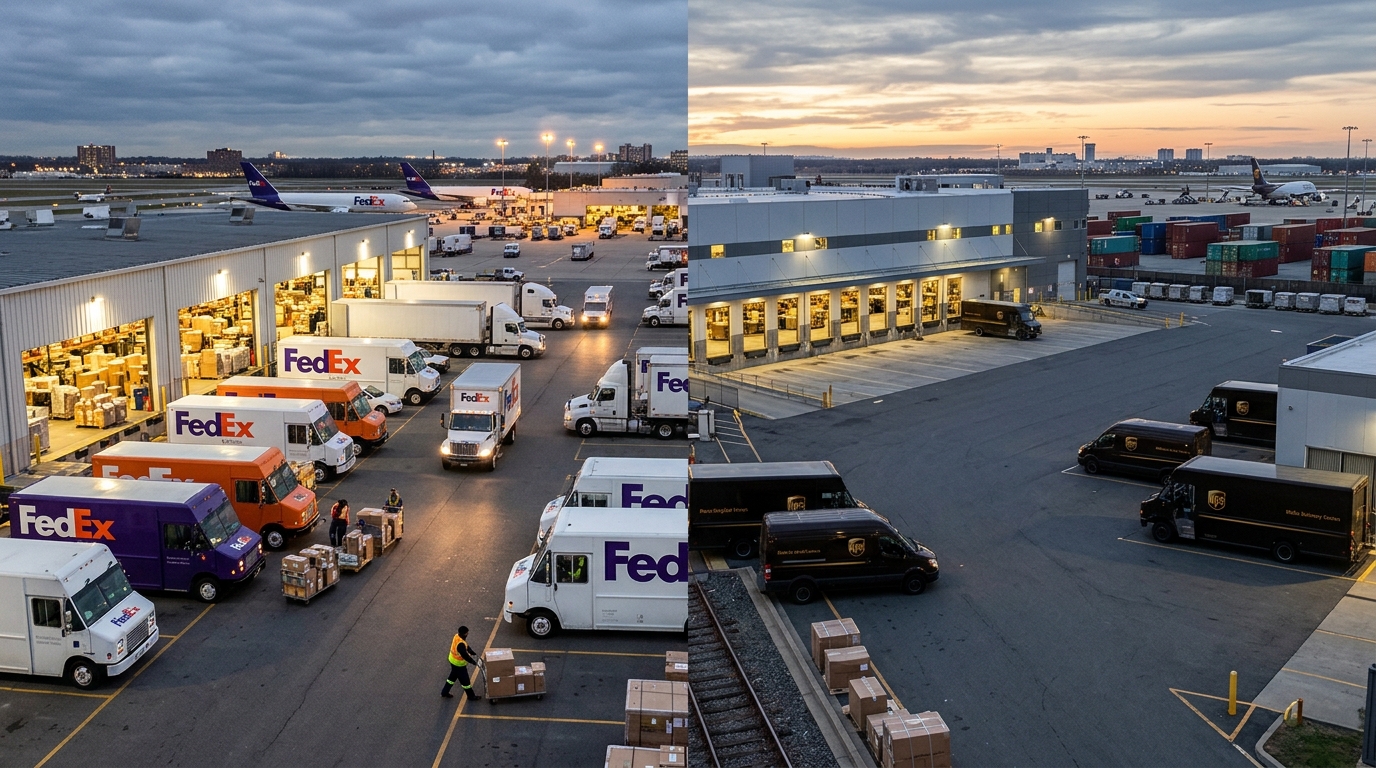
Two Carriers, Two Holiday Strategies
The contrast with UPS, which reported Tuesday, is striking. UPS CEO Carol Tome said the company’s focus on more lucrative business means it can make more money delivering slightly fewer packages during its critical peak holiday season, with total average daily volume expected to be down 1.3% in the fourth quarter.
FedEx went the other direction. Management is forecasting roughly 2% average daily volume growth for peak, specifically the Black Friday through Christmas window. The company now expects about 12% full-year revenue growth, including approximately 4 percentage points from fuel-price-driven surcharge revenue, and expects current volume and yield trends to remain directionally similar to Q3.
The split matters because neither company is guessing randomly. UPS completed a deliberate plan to cut Amazon volume by more than 50% by the second half of 2026 and is now running a leaner, higher-margin operation heading into holiday. FedEx, meanwhile, is leaning into volume, with B2B services driving a large share of the quarter’s growth. Sixty percent of FedEx revenue is B2B.
What the Freight Data Says About the Consumer
Here is the part most coverage misses. FedEx’s 12% revenue growth is not a clean consumer signal. Revenue growth was supported by approximately four percentage points from fuel-price-driven surcharge revenue, with the remaining eight percentage points coming from core operational improvements including base yield expansion and strategic volume growth in premium services. Strip the fuel surcharge tailwind out and the underlying rate is closer to 8%: real, but more measured than the headline implies.
The fuel surcharge math is only one layer of complexity in the current freight environment. Companies built to process rapid trade-rule changes have been direct beneficiaries of the same cross-border compliance pressure that is reshaping freight volumes.
On the consumer side specifically, UPS CEO Tome said the outlook for the holiday season is strong as U.S. consumers continue spending despite pressures from rising inflation and prices at the pump. Yet UPS framed that strength as a K-shaped reality: “It’s a bit of a K-curve, for sure. If you have assets, you are spending. If you don’t, you are stretched.”
FedEx’s international segment offers a separate read. International operations significantly outperformed, with revenue climbing 17% to $7.5 billion and adjusted operating income surging 52% to $297 million. International freight revenue was up 28%, driven by a 15% increase in average daily freight pounds and specialized B2B vertical demand. Cross-border B2B volumes holding up at that rate, even with global trade policy uncertainty, suggests supply chains are restocking rather than contracting.
The Asset Sale Underneath
One structural detail buried in the 10-Q deserves attention: on October 1, 2026, FedEx completed the sale of FedEx Supply Chain to CMA CGM Group for an enterprise value of $1.4 billion. The business joins CEVA Logistics. Combined with the FedEx Freight spin-off earlier this year, FedEx is now a sharply narrower company, concentrating capital on the parcel and air freight lanes where it has the clearest pricing power.
XPO reports this morning, and its LTL tonnage trends will be the next data point in this same read. Analysts are looking for solid year-over-year growth in XPO’s quarterly revenue. If XPO confirms volume growth alongside FedEx’s raised volume guidance, the freight complex as a whole is telling a more constructive holiday story than the macro headlines suggest. If XPO’s tonnage disappoints the way its own prior-quarter data hinted, the FedEx confidence looks more company-specific than cyclical.
Watch XPO’s North American LTL tonnage per day figure. That single line will either confirm FedEx’s raised peak season bet or complicate it.