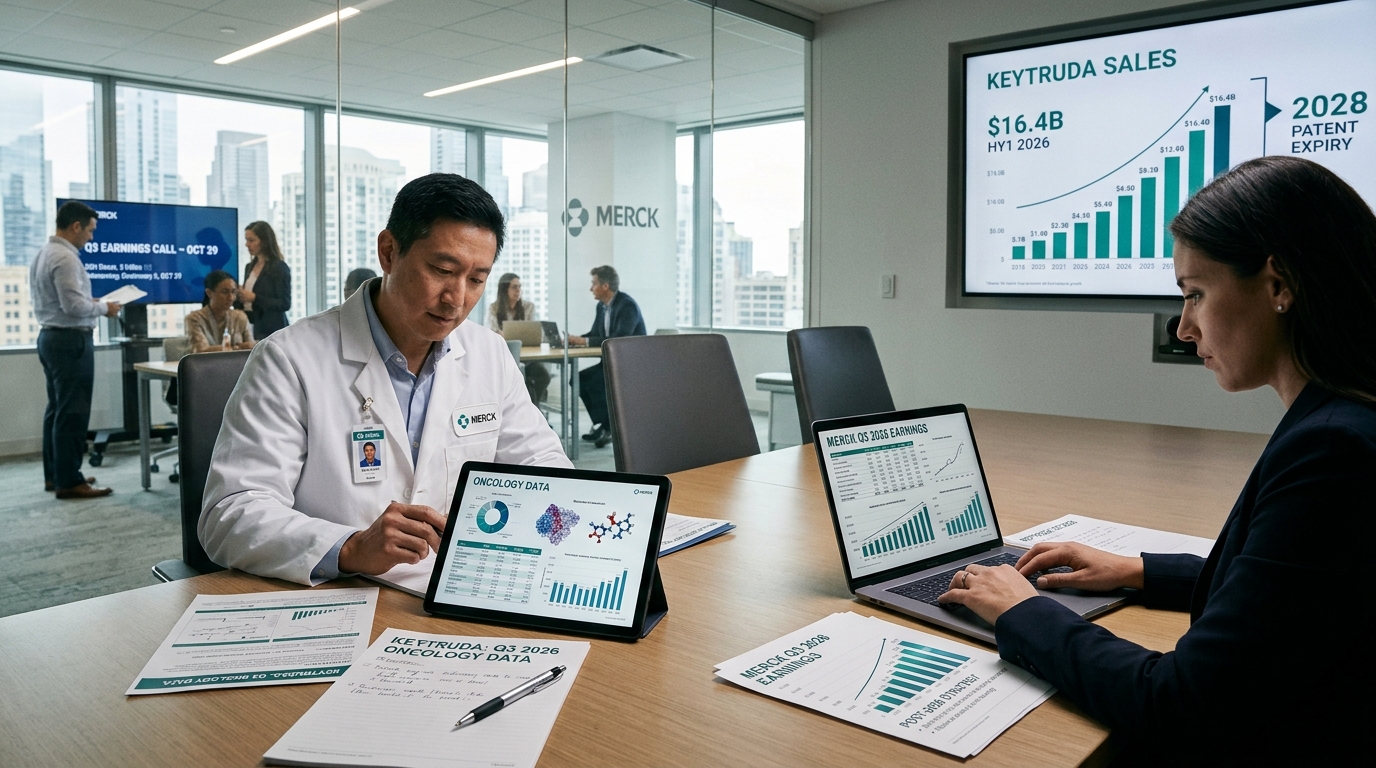
Keytruda generated $16.4 billion in sales in just the first six months of 2026. It accounts for more than 55% of Merck’s pharmaceutical sales. And in 2028, its U.S. patent expires. That tension has hovered over MRK for years. This week, investors get the most detailed answer yet on how Merck plans to live with it.
The Q3 2026 earnings call is set for October 29 at 9:00 a.m. ET. Merck is also hosting a hybrid oncology investor event in Madrid to coincide with the ESMO 2026 Congress, where management is scheduled to provide an update on the oncology portfolio, pipeline progress, and strategic priorities. That event takes place today, October 26. Two high-stakes disclosures in three days, both focused on the same existential question.
What the Numbers Have to Show
Last quarter, revenue grew 5% to $16.61 billion, driven by newer products despite a slight decline in Keytruda sales. Consensus expects Q3 revenue of around $17.3 billion, roughly flat with last year’s $17.28 billion, while adjusted EPS is expected to come in around $2.13, down roughly 18%. The earnings compression reflects one-time acquisition charges, not operational deterioration, but the headline figure will test investor patience heading into a patent-cliff year.
The Zacks consensus estimate for Keytruda’s Q3 sales stands at $7.45 billion. The subcutaneous formulation, Keytruda Qlex, is the growth variable within that figure. Keytruda generated $16.40 billion in total sales in the first six months of 2026, with Keytruda Qlex contributing $590 million during that period. The ramp from $128 million in Q1 to $463 million in Q2 was the kind of trajectory that justifies the conversion story. But complications have emerged.
The Subcutaneous Complication
A specialized Dutch patent court in The Hague ruled on October 7 that Merck infringed Halozyme’s EP622 patent covering its MDASE technology, and ordered Merck’s European marketing entity to stop manufacturing, marketing, importing, and distributing Keytruda SC across eight countries: Belgium, Denmark, France, Ireland, Italy, Sweden, Switzerland, and the Netherlands. The Netherlands case is part of a broader offensive by Halozyme, which also won a legal proceeding in Germany and is challenging Merck in a U.S. court. Merck said it strongly disagrees with the ruling and intends to fight. The IV formulation is unaffected. But the Q3 call will need to address how much the European injunction clouds the Qlex growth curve that investors have been underwriting.
The Pipeline That Changes the Math
The more important story arriving this week is intismeran. The Phase 3 INTerpath-001 readout, presented at ESMO, represents the first positive Phase 3 result for an individualized neoantigen therapy and for an mRNA-based cancer treatment, as well as the first Phase 3 study to demonstrate a clinically meaningful improvement over pembrolizumab alone in the adjuvant setting for resected melanoma. The combination of intismeran plus Keytruda reduced the risk of recurrence or death by 42% compared to Keytruda alone, and also significantly reduced the risk of distant metastasis or death by 38%.
The commercial logic is direct: intismeran, developed jointly with Moderna, would be sold alongside Keytruda and then alongside Keytruda Qlex in high-risk NSCLC. Moderna has already begun preparing for potential launch and scale-up of intismeran following the positive Phase 3 results. At the ESMO investor event, management plans to frame how INTerpath-001, TroFuse-005, and KEYNOTE-C93 fit into the next cohort of more than 20 planned growth drivers.
Bull Case, Bear Case
The bull case is straightforward: the Keytruda franchise is not a cliff so much as a transition. Qlex extends the brand, intismeran extends the revenue line, and a pipeline spanning renal cell carcinoma, bladder cancer, and endometrial cancer keeps expanding the addressable patient base. Year to date, shares are up about 38%. The market has already begun pricing some of this in.
The bear case is that the Halozyme injunction disrupts the Qlex ramp precisely when Merck needs it most, overall survival data for intismeran is not yet in hand, and the main risk remains Keytruda erosion after 2028 outrunning new launches. Management raised 2026 revenue guidance after Q2, but analysts have continued trimming earnings expectations amid concerns about Keytruda’s future.
What to Watch Thursday
Three things matter on the Q3 call: Qlex revenue and any guidance revision tied to the European injunction; updated full-year sales guidance; and management’s framing of the intismeran commercial timeline. If Merck can show the mRNA franchise accelerating while Qlex holds its U.S. trajectory, the 2028 cliff starts to look more like a speed bump than a wall.