October 13, 2026
Bonus Content: PJM Capacity Prices Surged 833%. Now Governors Want Them Down. Your Dividends Depend on Which Side of That Fight You Own.
Dear Reader,
Last year, the richest man on Earth said the quiet part out loud.
Elon Musk called the U.S. dollar – in a single word – “hopeless.”
But he wasn’t just venting. He was offering a clue to his latest and greatest innovation yet.
Now, with the blessing of President Trump and the U.S. Treasury, it’s finally about to go “live.”
And investors who move early could see the biggest gains of the decade.
Regards,
Ian King
Chief Strategist, Strategic Fortunes
PJM Capacity Prices Surged 833%. Now Governors Want Them Down. Your Dividends Depend on Which Side of That Fight You Own.
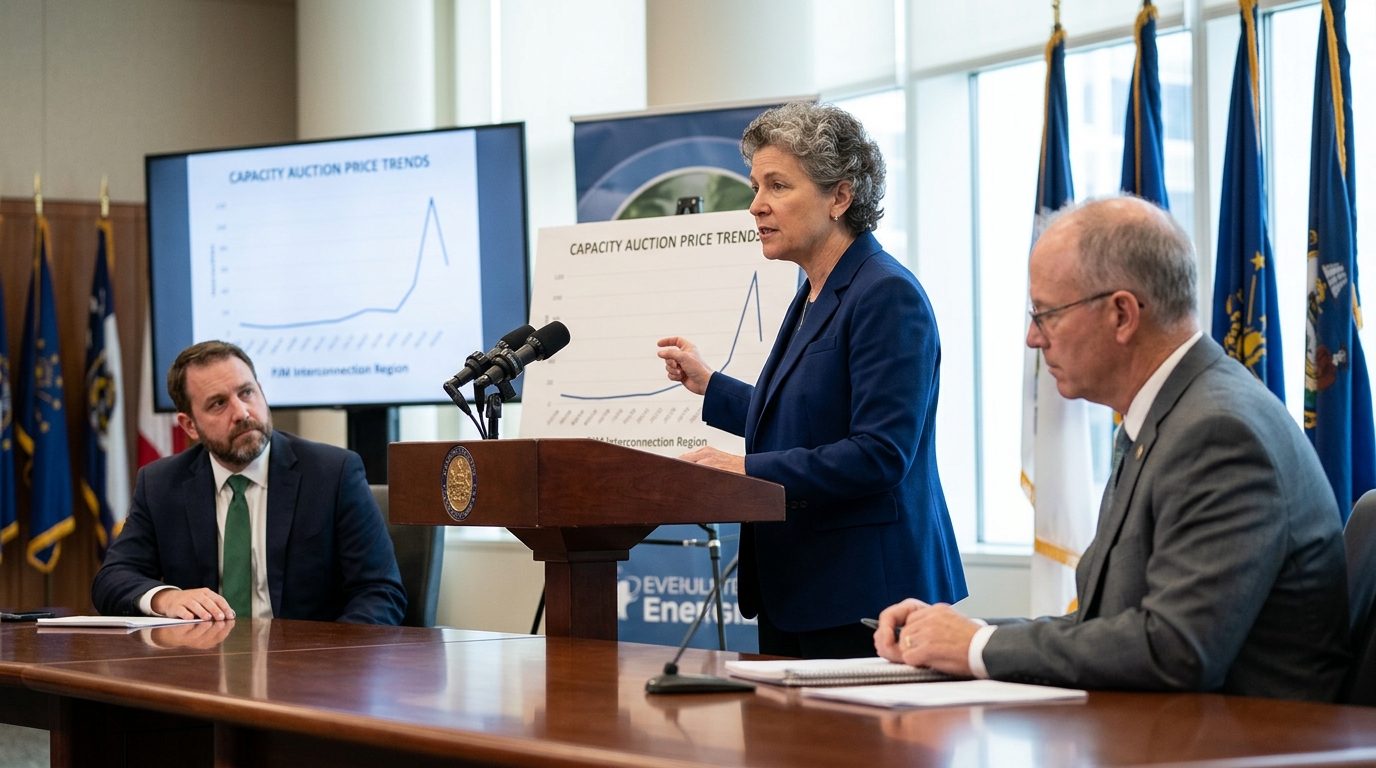
Most income investors who hold utility stocks in PJM territory have never stopped to ask a simple question: does my company collect those capacity payments, or write the check for them? Thirteen governors and the mayor of Washington, DC answered that question for you last Thursday, October 8, 2026, when they formally launched a coalition demanding lower capacity prices from the grid operator. The two groups are not in the same trade.
What the Governors Actually Did
At a summit in Chicago, governors from 13 states and the DC mayor signed a memorandum of understanding formally creating the PJM Governors’ Collaborative, coordinating efforts to reform PJM Interconnection, which oversees wholesale electricity transmission across 13 states and the District of Columbia. The coalition spans Democratic and Republican governors.
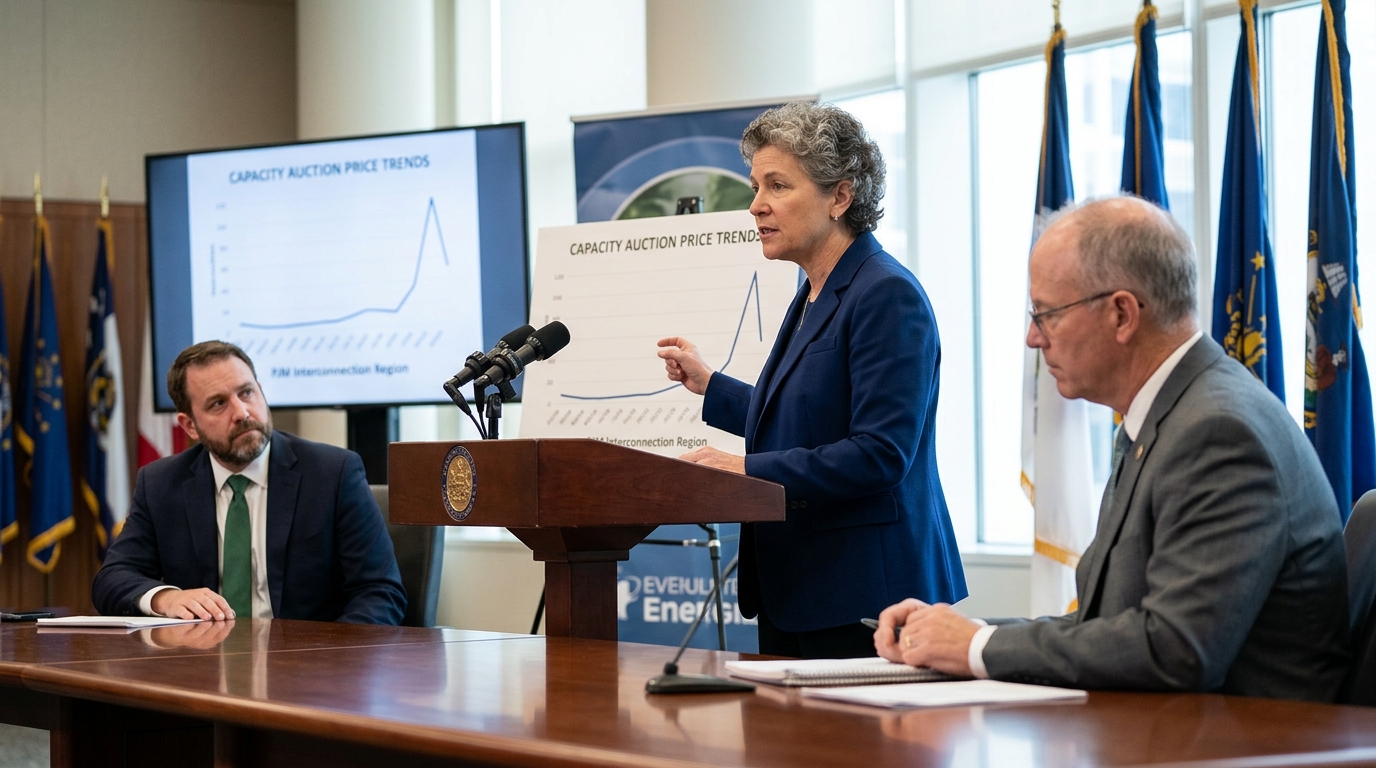
The central grievance is the rising cost of PJM’s capacity market, which pays power suppliers to commit to having electricity available when demand is highest. The coalition agreement points to an 833% increase in capacity auction prices for the 2025-26 delivery year. Prices have remained elevated in subsequent auctions. In July 2026, PJM’s auction for the 2028-29 delivery year produced a price of $325 per megawatt-day, the maximum allowed under a federally approved price cap, securing $16.4 billion in capacity commitments but falling 6,831 megawatts short of PJM’s reliability requirement.
The Line That Divides Your Portfolio
Here is where income investors need to pay close attention. The capacity market does not treat every electricity company the same way.
Merchant generators, including Constellation Energy (CEG), Vistra (VST), Talen Energy (TLN), and NRG Energy (NRG), are the ones collecting these payments. According to PJM’s independent market monitor, Constellation is one of the largest PJM capacity owners, with 20.3 GW, and it runs the biggest nuclear fleet in the US. In its 2Q 2026 materials, NRG showed PJM capacity revenue projected to grow from $644 million in 2026 to $781 million in 2028. Every dollar the governors shave off capacity prices is a dollar removed from these companies’ forward earnings. CEG’s small dividend, currently around 0.6%, rests on merchant cash flows that are now politically targeted.
Regulated utilities tell the opposite story. Exelon (EXC), PPL Corporation (PPL), FirstEnergy (FE), and American Electric Power (AEP) are distribution and transmission companies that pass capacity costs through to ratepayers rather than collecting them as revenue. Lower capacity prices reduce the cost burden on their customers, ease political pressure in rate cases, and make their next regulatory filing easier to defend. Exelon has described a four-year $41.3 billion capital plan, closely tied to regulatory decisions on transmission, modernization, and affordability, so any shift toward a more constructive regulatory environment could improve how that investment translates into earnings growth and dividend support. PPL raised its quarterly dividend 4.6% in February 2026 to $0.2850 per share, and a governor-driven reduction in capacity costs would only strengthen that kind of incremental increase going forward.
Why This Is an Income Question, Not Just a Policy Story
The governors argue that ratepayers and their elected representatives have no meaningful opportunity to vote on behalf of the public interest within PJM’s stakeholder decision-making process, and that requests for greater representation have been ignored. They plan to develop common positions on energy policy, obtain independent technical assistance, and coordinate their dealings with PJM and federal regulators. With midterms 23 days away on November 3, 2026, and electricity bills a central campaign issue across Ohio, Pennsylvania, and Michigan, these governors have real political leverage, not just a letter.
The structural forces driving PJM prices, a combination of coal and gas plant retirements, surging data center load, and tighter reliability modeling, have not changed. Any political cap that suppresses prices below where supply and demand would otherwise clear creates a reliability risk that benefits firms with locked-in contracted revenue, namely the nuclear generators with long-term power purchase agreements.
The Wealth-Building Takeaway
Owning both regulated utilities and merchant generators in the same PJM region without distinguishing them is not diversification. It is confusion. The governor coalition has now made the fault line explicit: regulated utilities with strong capital plans, predictable rate cases, and growing dividends sit on one side; merchant generators whose earnings depend on capacity prices the governors are working to compress sit on the other. Know which side of that line each position you hold actually occupies.